EX-99.1
Published on October 28, 2026
I N V E S T O R P R E S E N T A T I O N Hovde Group 2026 Financial Services Conference Orlando | November 4 - 6, 2026 N Y S E : C B N A
2Chain Bridge Bancorp, Inc. This presentation contains forward-looking statements within the meaning of the U.S. federal securities laws. Forward-looking statements involve risks and uncertainties. You should not place undue reliance on forward-looking statements because they are subject to numerous uncertainties and factors relating to our operations and business, all of which are difficult to predict and many of which are beyond our control. Forward-looking statements include information concerning our possible or assumed future results of operations. These forward-looking statements are generally identified by the use of forward-looking terminology, including the terms “anticipate,” “believe,” “could,” “estimate,” “expect,” “intend,” “may,” “might,” “plan,” “potential,” “predict,” “project,” “should,” “target,” “will,” “would” and, in each case, their negative or other variations or comparable terminology and expressions. Actual results, performance, or achievements could differ materially from those contemplated, expressed, or implied by the forward-looking statements. Any forward-looking statements presented herein are made only as of the date of this presentation, and the Company does not undertake any obligation to update or revise any forward-looking statements to reflect changes in assumptions, new information, the occurrence of unanticipated events, or otherwise, except as required by law. Forward-looking statements include, among other things, statements relating to: (i) changes in trade, monetary and fiscal policies of, and other activities undertaken by, governments, agencies, central banks and similar organizations, including the effects of United States federal government spending and tariffs; (ii) the level of, or changes in the level of, interest rates and inflation, including the effects on our net interest income, noninterest income, and the market value of our investment and loan portfolios;(iii) the level and composition of our deposits, including our ability to attract and retain, and the seasonality of, client deposits, including those in the ICS®1 network, as well as the amount and timing of deposit inflows and outflows, including during the fourth quarter of 2026 and early 2027, and the concentration of our deposits; (iv) our future net interest margin, net interest income, net income, and return on equity; (v) our political organization clients’ fundraising and disbursement activities; (vi) the level and composition of our loan portfolio, including our ability to maintain the credit quality of our loan portfolio; (vii) current and future business, economic and market conditions in the United States generally or in the Washington, D.C. metropolitan area in particular; (viii) the effects of disruptions or instability in the financial system, including as a result of the failure of a financial institution or other participants in it, or geopolitical instability, including war, terrorist attacks, pandemics and man-made and natural disasters; (ix) the impact of, and changes, in applicable laws, regulations, regulatory expectations and accounting standards and policies; (x) our likelihood of success in, and the impact of, legal, regulatory or other actions, investigations or proceedings related to our business; (xi) adverse publicity or reputational harm to us, our senior officers, directors, employees or clients; (xii) our ability to effectively execute our growth plans or other initiatives; (xiii) changes in demand for our products and services; (xiv) our levels of, and access to, sources of liquidity and capital; (xv) the ability to attract and retain essential personnel or changes in our essential personnel; (xvi) our ability to effectively compete with banks, non-bank financial institutions, and financial technology firms and the effects of competition in the financial services industry on our business; (xvii) the emergence, adoption and evolution of new technologies and payment methods, including stablecoins, digital assets, blockchains and other technologies based on distributed ledgers, and their effects on competition and our business; (xviii) the development, use and regulation of artificial intelligence, including by us, our vendors and our competitors; (xix) the effectiveness of our risk management and internal disclosure controls and procedures; (xx) any failure or interruption of our information and technology systems, including any components provided by a third party; (xxi) our ability to identify and address cybersecurity threats and breaches; (xxii) our ability to keep pace with technological changes; (xxiii) our ability to receive dividends from Chain Bridge Bank, N.A. and satisfy our obligations as they become due; (xxiv) the incremental costs of operating as a public company; (xxv) our ability to meet our obligations as a public company, including our obligation under Section 404 of the Sarbanes-Oxley Act; and (xxvi) the effect of our dual-class structure and the concentrated ownership of our Class B common stock, including beneficial ownership of our shares by members of the Fitzgerald Family. You should not rely upon forward-looking statements as predictions of future events. We have based the forward-looking statements contained in this presentation primarily on our current expectations and projections about future events and trends that we believe may affect our business, financial condition, results of operations and prospects. The outcome of the events described in these forward-looking statements is subject to risks, uncertainties and other factors, including the risks described in the “Risk Factors” section of the Company’s most recent Annual Report on Form 10- K for the year ended December 31, 2025, and in the Company’s subsequent filings with the Securities and Exchange Commission, including its Quarterly Reports on Form 10-Q, available at the Securities and Exchange Commission’s website (www.sec.gov). Cautionary Note Regarding Forward-Looking Statements 1. IntraFi, ICS, IntraFi Cash Service, and One-Way Sell are registered service marks of IntraFi LLC.
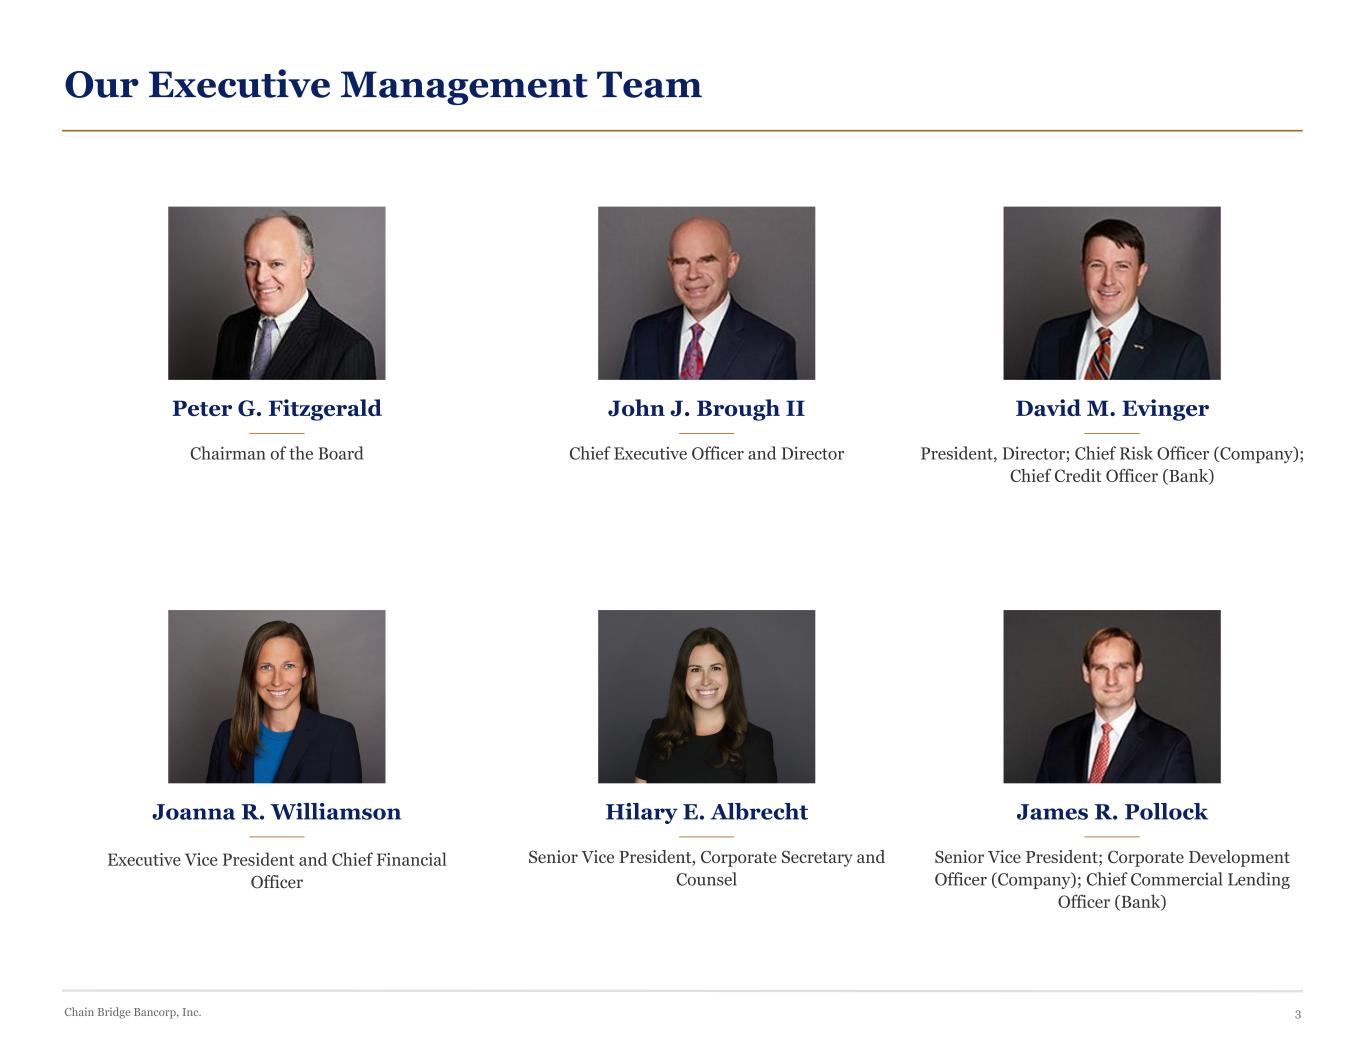
3Chain Bridge Bancorp, Inc. Our Executive Management Team Peter G. Fitzgerald Chairman of the Board John J. Brough II Chief Executive Officer and Director David M. Evinger President, Director; Chief Risk Officer (Company); Chief Credit Officer (Bank) Joanna R. Williamson Executive Vice President and Chief Financial Officer Hilary E. Albrecht Senior Vice President, Corporate Secretary and Counsel James R. Pollock Senior Vice President; Corporate Development Officer (Company); Chief Commercial Lending Officer (Bank)
4Chain Bridge Bancorp, Inc. Company Overview Chain Bridge Bancorp, Inc. is a Delaware-chartered bank holding company and the parent of its wholly-owned subsidiary, Chain Bridge Bank, N.A., a nationally chartered commercial bank with fiduciary powers granted by the Office of the Comptroller of the Currency. ■ Founded: Incorporated on May 26, 2006; Bank opened August 6, 2007 ■ Trust Powers: Granted by the OCC on March 5, 2020; trust activities initiated on September 18, 2020 ■ Headquarters: McLean, VA (approximately 5 miles from Washington, D.C.) ■ IPO: October 2024 – Issued 1,992,897 shares of Class A common stock, par value $0.01 per share, at $22.00 per share – IPO and partial exercise of the underwriters’ over-allotment option resulted in approximately $36.5 million in net proceeds to the Company ■ Listing: Traded on the New York Stock Exchange (NYSE) under ticker symbol “CBNA” ■ Index Membership: As of June 30, 2025, the Company was added to the Russell 3000® Index and certain other Russell indices. Membership in these indices is determined annually by FTSE Russell and is subject to change. As of June 30, 2026, the Company remains a member of these indices.
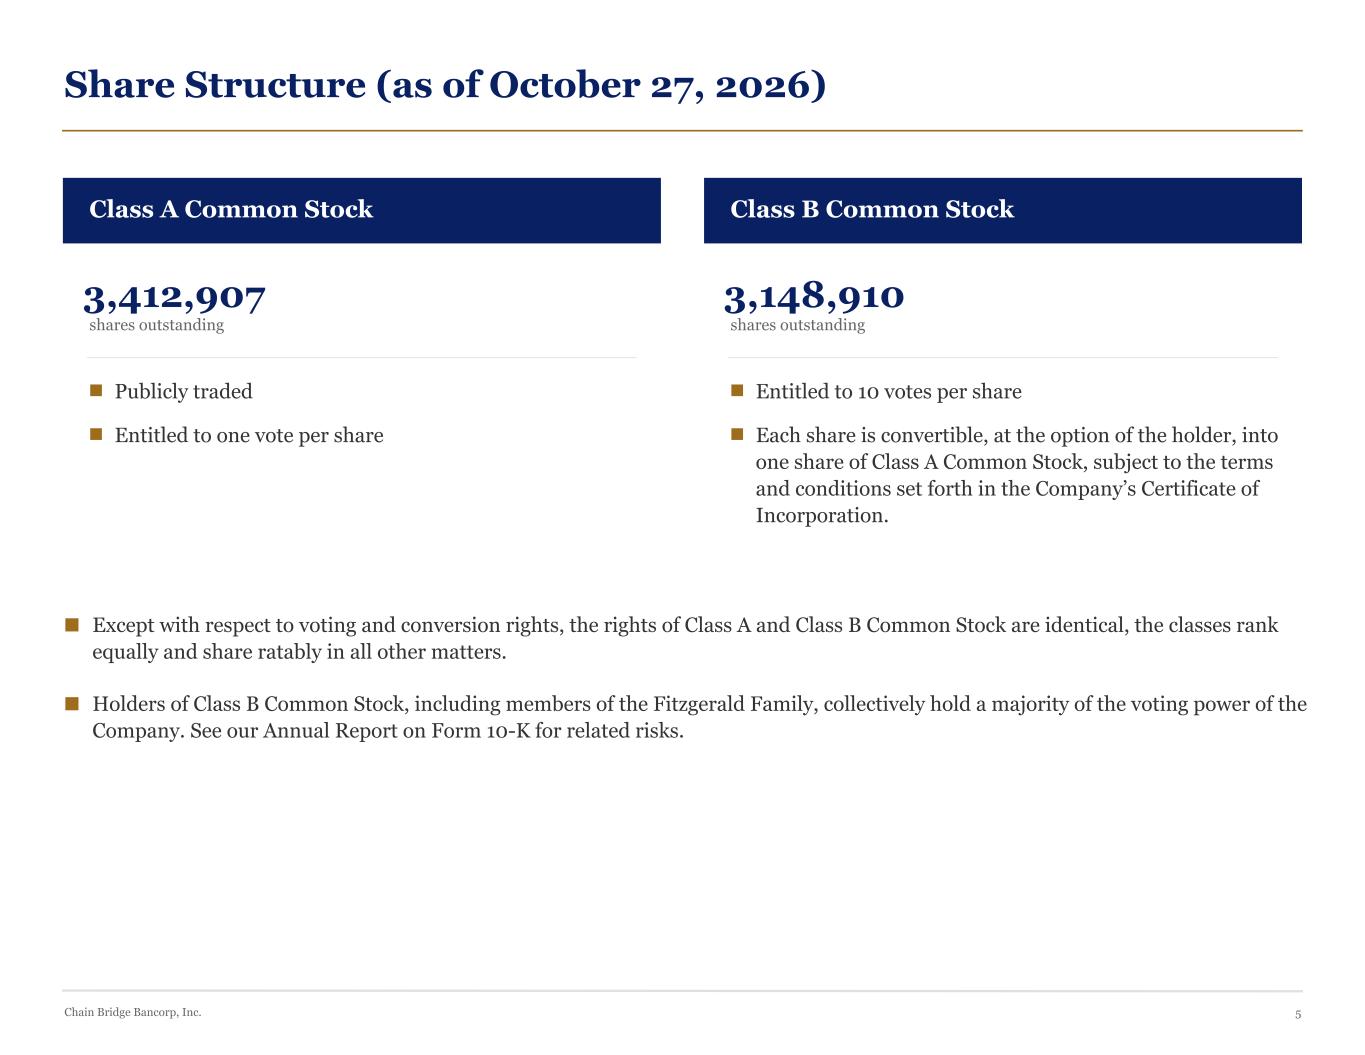
5Chain Bridge Bancorp, Inc. Share Structure (as of October 27, 2026) Class A Common Stock shares outstanding ■ Publicly traded ■ Entitled to one vote per share Class B Common Stock shares outstanding ■ Entitled to 10 votes per share ■ Each share is convertible, at the option of the holder, into one share of Class A Common Stock, subject to the terms and conditions set forth in the Company’s Certificate of Incorporation. ■ Except with respect to voting and conversion rights, the rights of Class A and Class B Common Stock are identical, the classes rank equally and share ratably in all other matters. ■ Holders of Class B Common Stock, including members of the Fitzgerald Family, collectively hold a majority of the voting power of the Company. See our Annual Report on Form 10-K for related risks. 3,412,907 3,148,910
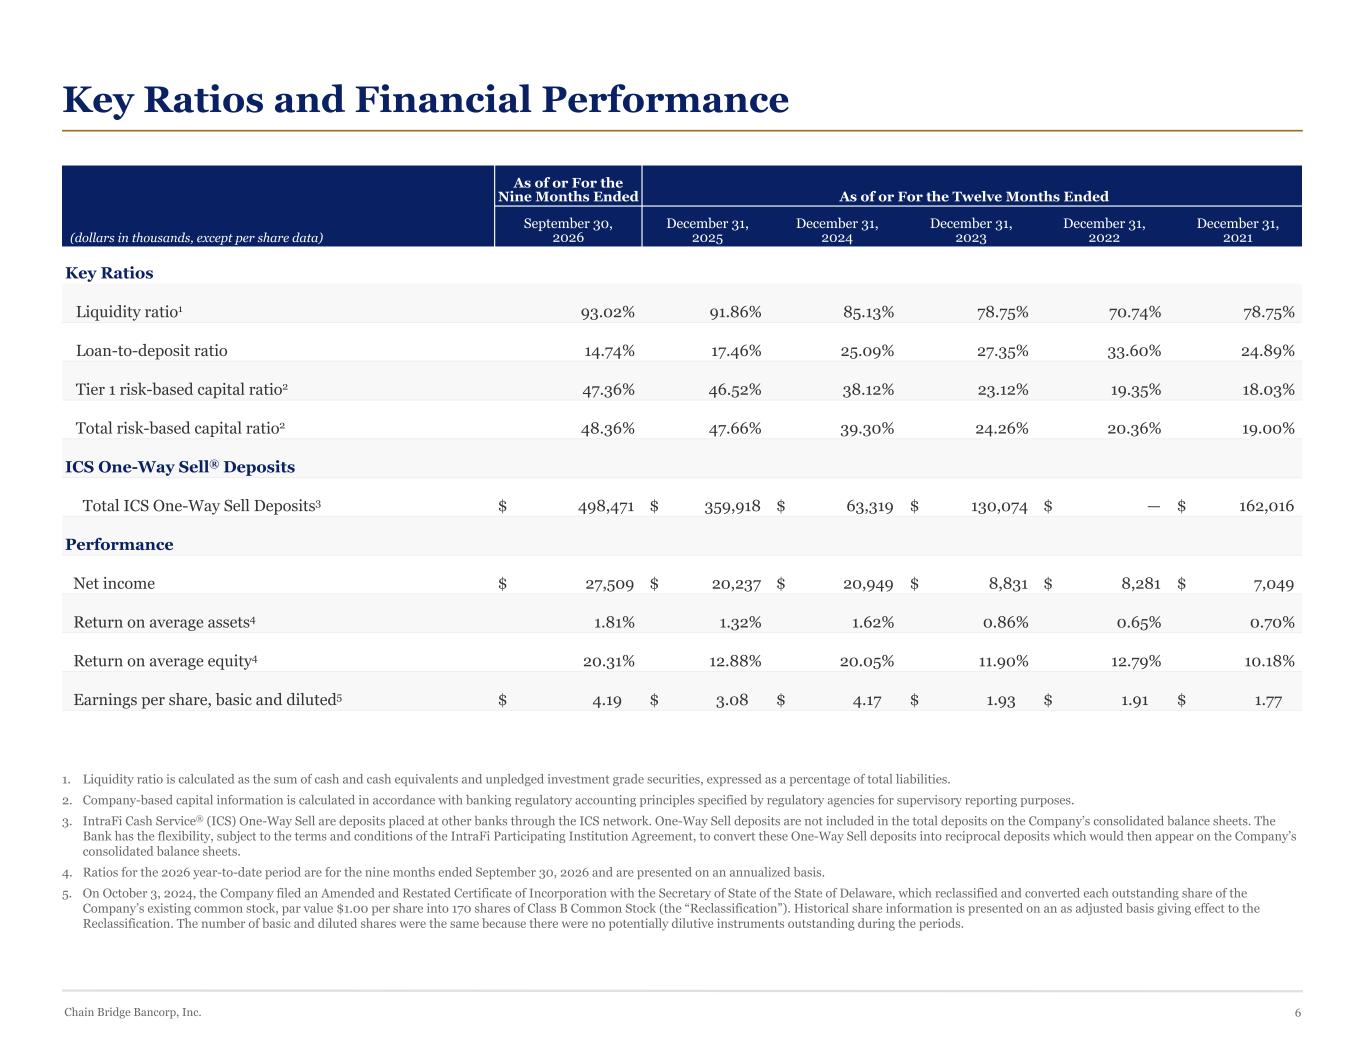
6Chain Bridge Bancorp, Inc. Key Ratios and Financial Performance As of or For the Nine Months Ended As of or For the Twelve Months Ended (dollars in thousands, except per share data) September 30, 2026 December 31, 2025 December 31, 2024 December 31, 2023 December 31, 2022 December 31, 2021 Key Ratios Liquidity ratio1 93.02% 91.86% 85.13% 78.75% 70.74% 78.75% Loan-to-deposit ratio 14.74% 17.46% 25.09% 27.35% 33.60% 24.89% Tier 1 risk-based capital ratio2 47.36% 46.52% 38.12% 23.12% 19.35% 18.03% Total risk-based capital ratio2 48.36% 47.66% 39.30% 24.26% 20.36% 19.00% ICS One-Way Sell® Deposits Total ICS One-Way Sell Deposits3 $ 498,471 $ 359,918 $ 63,319 $ 130,074 $ — $ 162,016 Performance Net income $ 27,509 $ 20,237 $ 20,949 $ 8,831 $ 8,281 $ 7,049 Return on average assets4 1.81% 1.32% 1.62% 0.86% 0.65% 0.70% Return on average equity4 20.31% 12.88% 20.05% 11.90% 12.79% 10.18% Earnings per share, basic and diluted5 $ 4.19 $ 3.08 $ 4.17 $ 1.93 $ 1.91 $ 1.77 1. Liquidity ratio is calculated as the sum of cash and cash equivalents and unpledged investment grade securities, expressed as a percentage of total liabilities. 2. Company-based capital information is calculated in accordance with banking regulatory accounting principles specified by regulatory agencies for supervisory reporting purposes. 3. IntraFi Cash Service® (ICS) One-Way Sell are deposits placed at other banks through the ICS network. One-Way Sell deposits are not included in the total deposits on the Company’s consolidated balance sheets. The Bank has the flexibility, subject to the terms and conditions of the IntraFi Participating Institution Agreement, to convert these One-Way Sell deposits into reciprocal deposits which would then appear on the Company’s consolidated balance sheets. 4. Ratios for the 2026 year-to-date period are for the nine months ended September 30, 2026 and are presented on an annualized basis. 5. On October 3, 2024, the Company filed an Amended and Restated Certificate of Incorporation with the Secretary of State of the State of Delaware, which reclassified and converted each outstanding share of the Company’s existing common stock, par value $1.00 per share into 170 shares of Class B Common Stock (the “Reclassification”). Historical share information is presented on an as adjusted basis giving effect to the Reclassification. The number of basic and diluted shares were the same because there were no potentially dilutive instruments outstanding during the periods.
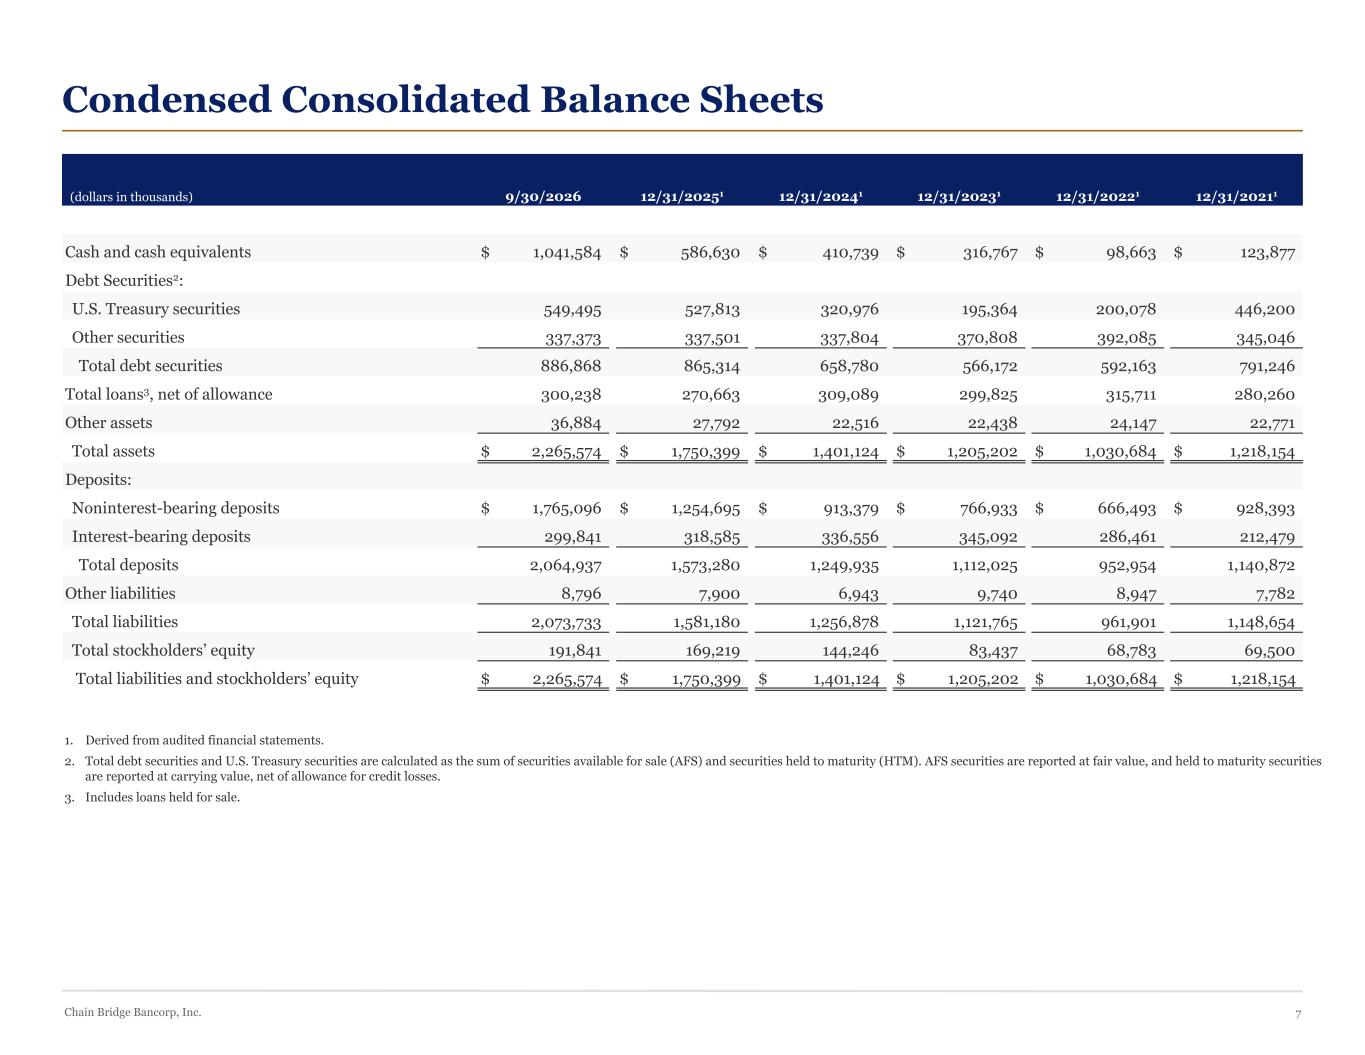
7Chain Bridge Bancorp, Inc. Condensed Consolidated Balance Sheets (dollars in thousands) 9/30/2026 12/31/20251 12/31/20241 12/31/20231 12/31/20221 12/31/20211 Cash and cash equivalents $ 1,041,584 $ 586,630 $ 410,739 $ 316,767 $ 98,663 $ 123,877 Debt Securities2: U.S. Treasury securities 549,495 527,813 320,976 195,364 200,078 446,200 Other securities 337,373 337,501 337,804 370,808 392,085 345,046 Total debt securities 886,868 865,314 658,780 566,172 592,163 791,246 Total loans3, net of allowance 300,238 270,663 309,089 299,825 315,711 280,260 Other assets 36,884 27,792 22,516 22,438 24,147 22,771 Total assets $ 2,265,574 $ 1,750,399 $ 1,401,124 $ 1,205,202 $ 1,030,684 $ 1,218,154 Deposits: Noninterest-bearing deposits $ 1,765,096 $ 1,254,695 $ 913,379 $ 766,933 $ 666,493 $ 928,393 Interest-bearing deposits 299,841 318,585 336,556 345,092 286,461 212,479 Total deposits 2,064,937 1,573,280 1,249,935 1,112,025 952,954 1,140,872 Other liabilities 8,796 7,900 6,943 9,740 8,947 7,782 Total liabilities 2,073,733 1,581,180 1,256,878 1,121,765 961,901 1,148,654 Total stockholders’ equity 191,841 169,219 144,246 83,437 68,783 69,500 Total liabilities and stockholders’ equity $ 2,265,574 $ 1,750,399 $ 1,401,124 $ 1,205,202 $ 1,030,684 $ 1,218,154 1. Derived from audited financial statements. 2. Total debt securities and U.S. Treasury securities are calculated as the sum of securities available for sale (AFS) and securities held to maturity (HTM). AFS securities are reported at fair value, and held to maturity securities are reported at carrying value, net of allowance for credit losses. 3. Includes loans held for sale.
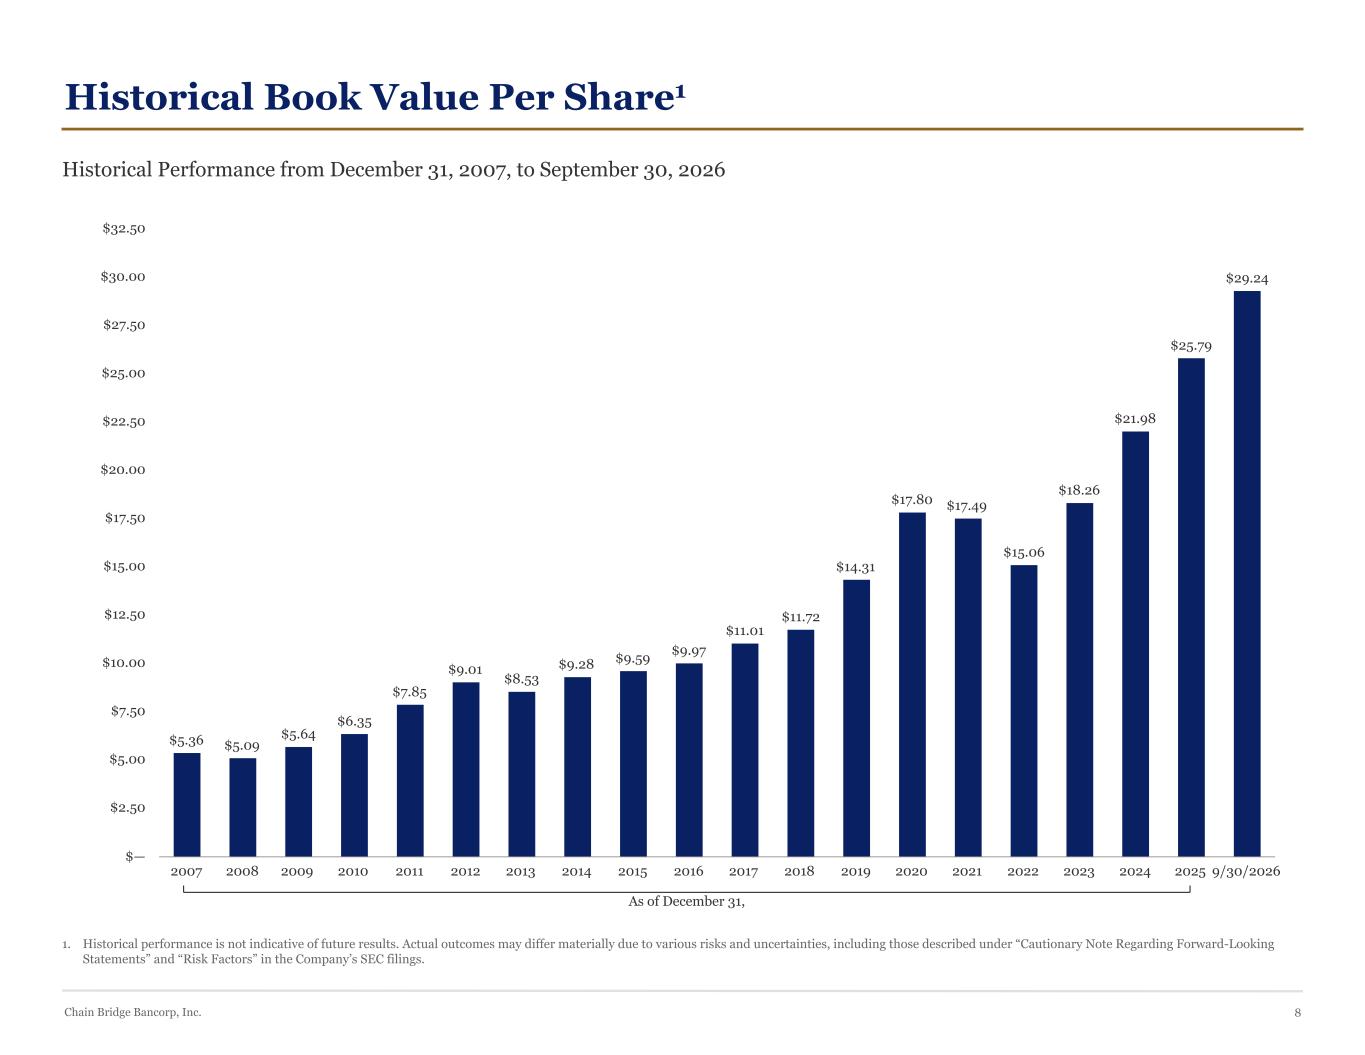
8Chain Bridge Bancorp, Inc. 1. Historical performance is not indicative of future results. Actual outcomes may differ materially due to various risks and uncertainties, including those described under “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in the Company’s SEC filings. Historical Performance from December 31, 2007, to September 30, 2026 Historical Book Value Per Share1 $5.36 $5.09 $5.64 $6.35 $7.85 $9.01 $8.53 $9.28 $9.59 $9.97 $11.01 $11.72 $14.31 $17.80 $17.49 $15.06 $18.26 $21.98 $25.79 $29.24 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 9/30/2026 $— $2.50 $5.00 $7.50 $10.00 $12.50 $15.00 $17.50 $20.00 $22.50 $25.00 $27.50 $30.00 $32.50 As of December 31,
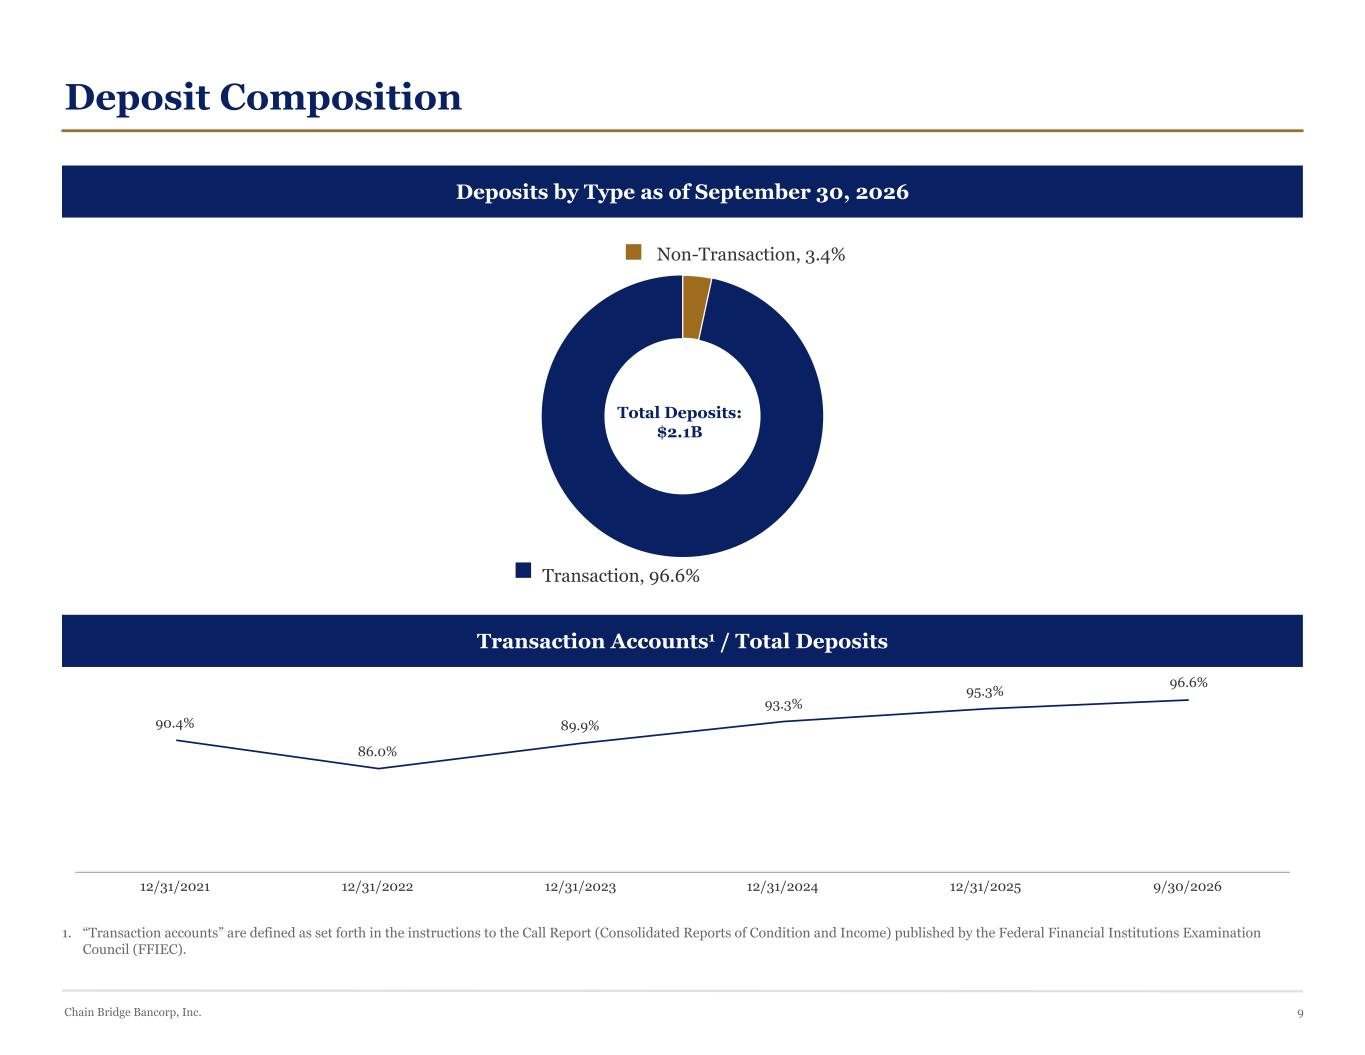
9Chain Bridge Bancorp, Inc. Transaction Accounts1 / Total Deposits Deposits by Type as of September 30, 2026 Deposit Composition Total Deposits: $2.1B 90.4% 86.0% 89.9% 93.3% 95.3% 96.6% 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 Non-Transaction, 3.4% Transaction, 96.6% 1. “Transaction accounts” are defined as set forth in the instructions to the Call Report (Consolidated Reports of Condition and Income) published by the Federal Financial Institutions Examination Council (FFIEC).
10Chain Bridge Bancorp, Inc. Experience in Serving Political Organizations ■ Political organizations have historically represented a significant part of our deposit base, including: – Campaign committees – Non-committee 527 organizations – Party committees (national, state, and local) – Leadership PACs – Corporate and trade association PACs – Joint fundraising committees – Super PACs and Hybrid PACs – Presidential inaugural committees ■ Our relationship officers assist political organizations with their banking needs, including: – Digital onboarding solutions – Payment processing – Transaction account services – Comprehensive treasury management platform
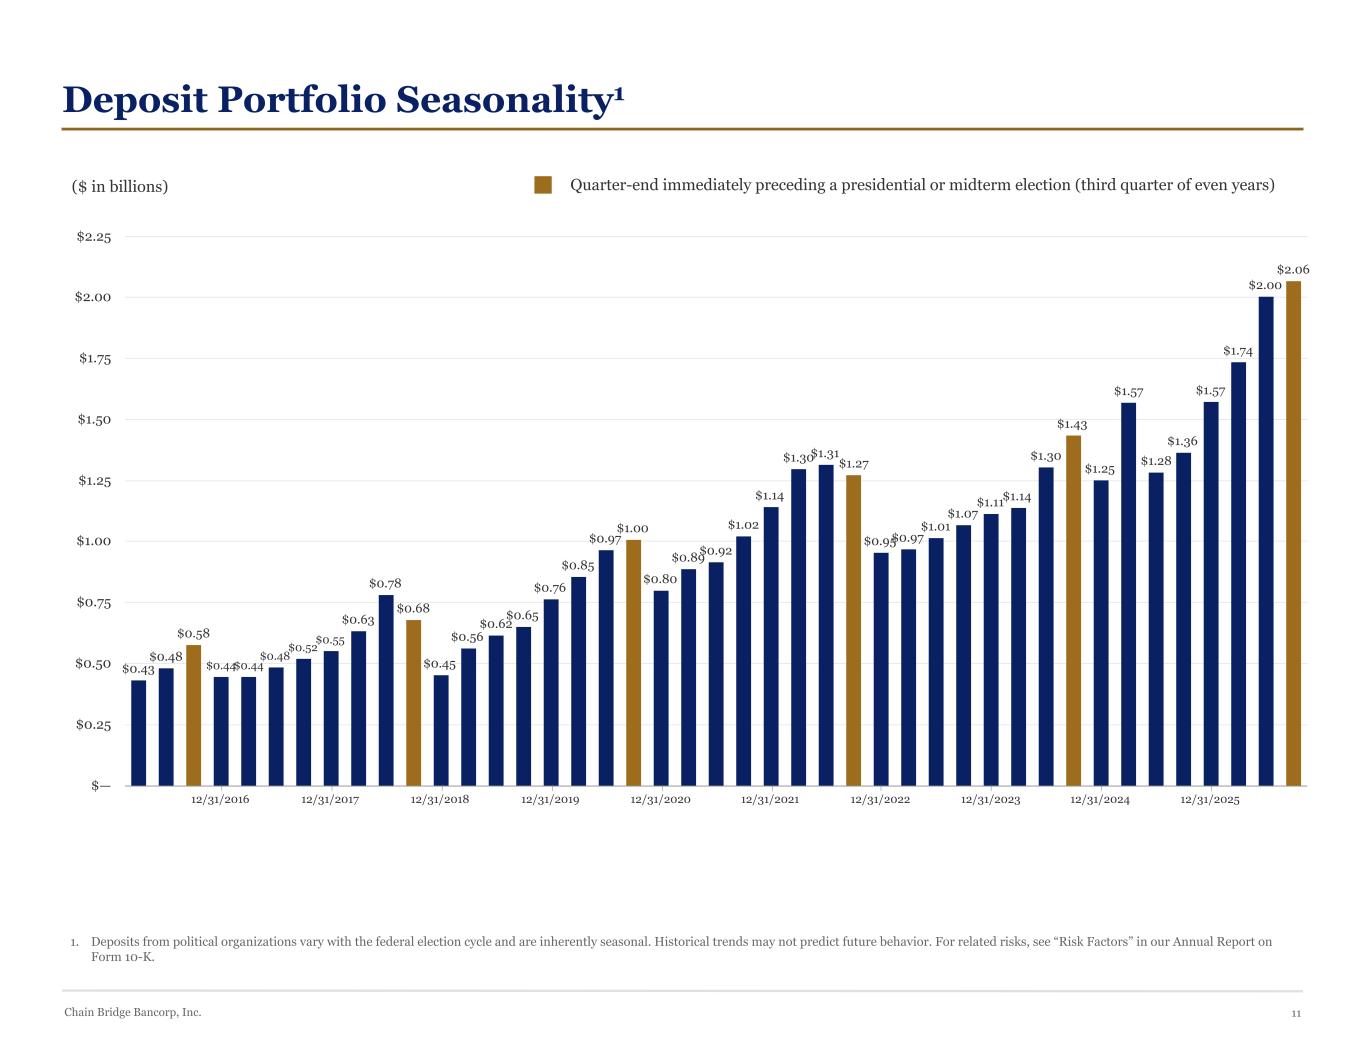
11Chain Bridge Bancorp, Inc. 1. Deposits from political organizations vary with the federal election cycle and are inherently seasonal. Historical trends may not predict future behavior. For related risks, see “Risk Factors” in our Annual Report on Form 10-K. Deposit Portfolio Seasonality1 ($ in billions) Quarter-end immediately preceding a presidential or midterm election (third quarter of even years) $0.43 $0.48 $0.58 $0.44$0.44 $0.48 $0.52 $0.55 $0.63 $0.78 $0.68 $0.45 $0.56 $0.62 $0.65 $0.76 $0.85 $0.97 $1.00 $0.80 $0.89$0.92 $1.02 $1.14 $1.30$1.31 $1.27 $0.95$0.97 $1.01 $1.07 $1.11$1.14 $1.30 $1.43 $1.25 $1.57 $1.28 $1.36 $1.57 $1.74 $2.00 $2.06 12/31/2016 12/31/2017 12/31/2018 12/31/2019 12/31/2020 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 $— $0.25 $0.50 $0.75 $1.00 $1.25 $1.50 $1.75 $2.00 $2.25 | | | | | | | | | |
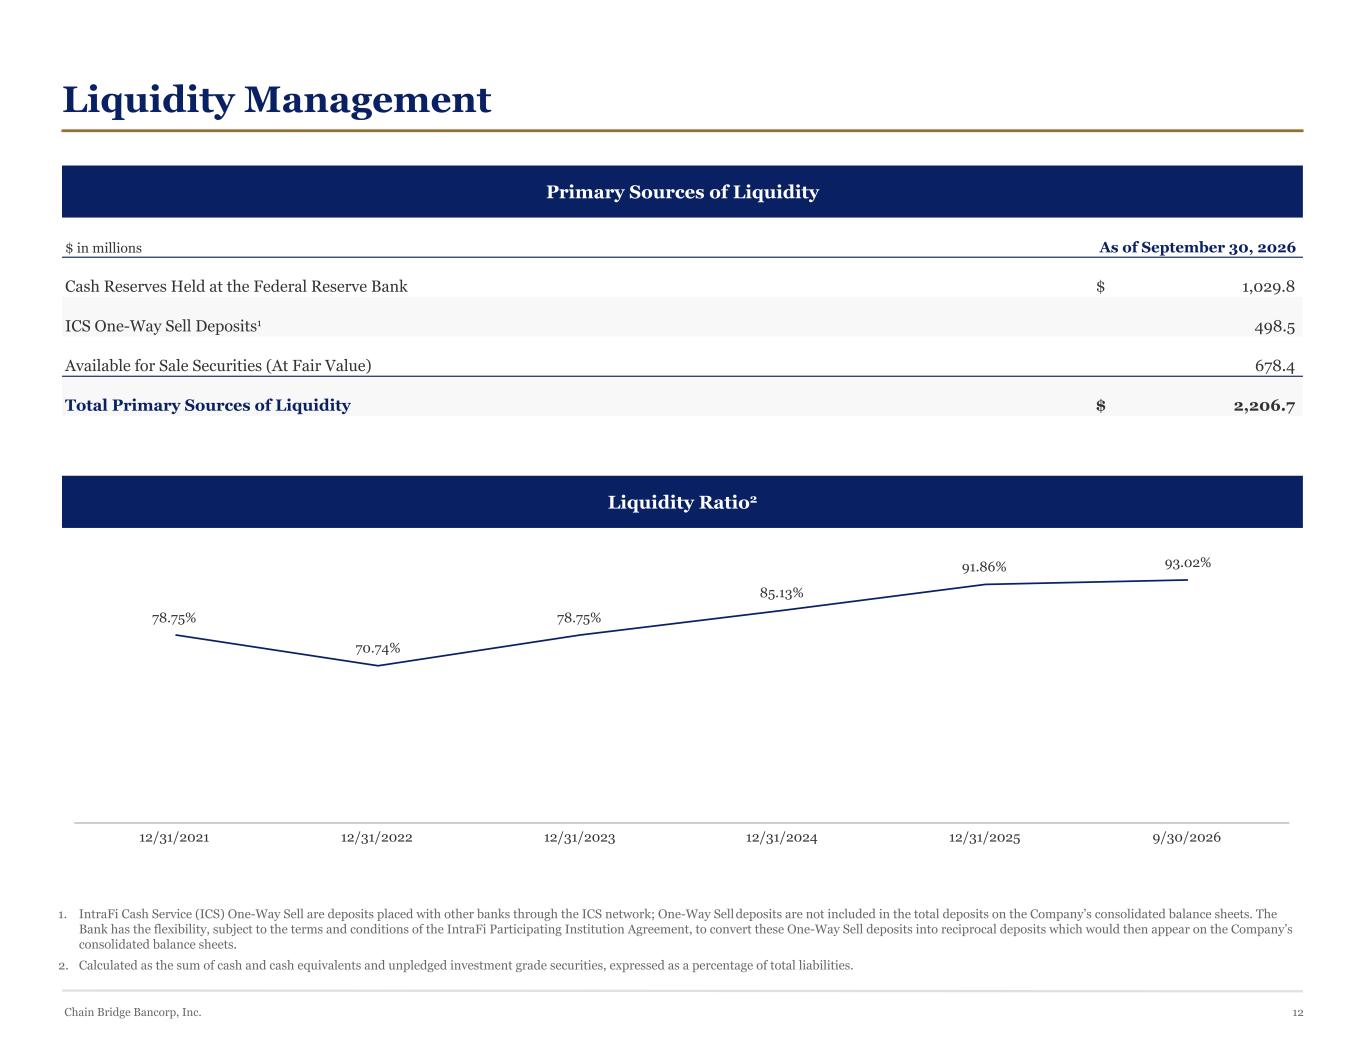
12Chain Bridge Bancorp, Inc. 1. IntraFi Cash Service (ICS) One-Way Sell are deposits placed with other banks through the ICS network; One-Way Sell deposits are not included in the total deposits on the Company’s consolidated balance sheets. The Bank has the flexibility, subject to the terms and conditions of the IntraFi Participating Institution Agreement, to convert these One-Way Sell deposits into reciprocal deposits which would then appear on the Company’s consolidated balance sheets. 2. Calculated as the sum of cash and cash equivalents and unpledged investment grade securities, expressed as a percentage of total liabilities. Liquidity Ratio2 Primary Sources of Liquidity 78.75% 70.74% 78.75% 85.13% 91.86% 93.02% 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 $ in millions As of September 30, 2026 Cash Reserves Held at the Federal Reserve Bank $ 1,029.8 ICS One-Way Sell Deposits1 498.5 Available for Sale Securities (At Fair Value) 678.4 Total Primary Sources of Liquidity $ 2,206.7 Liquidity Management
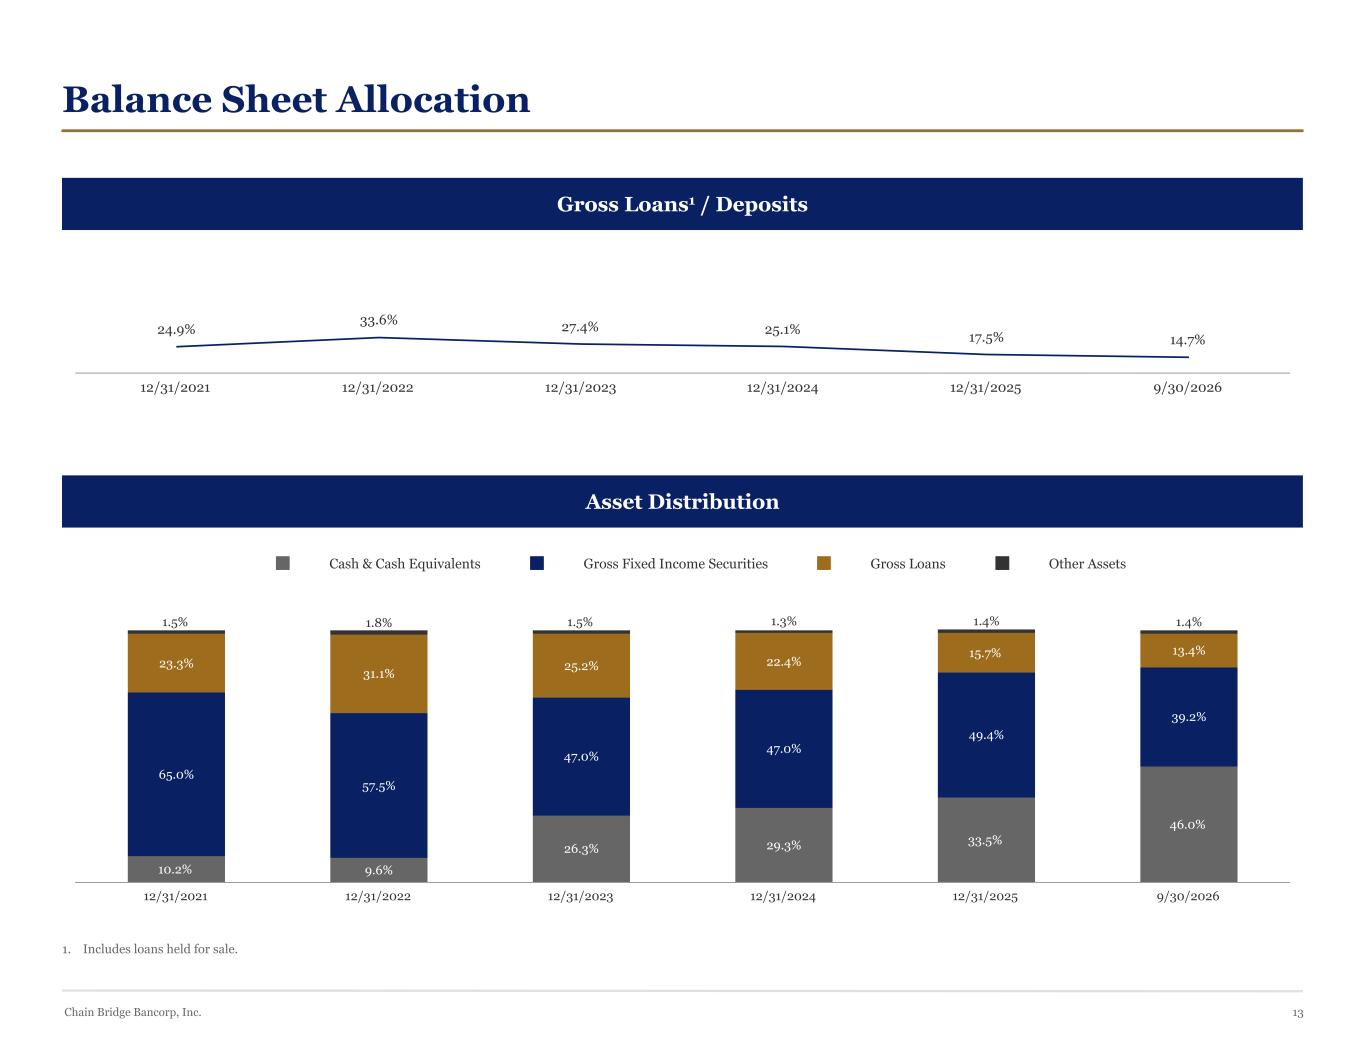
13Chain Bridge Bancorp, Inc. 1. Includes loans held for sale. Asset Distribution Gross Loans1 / Deposits 24.9% 33.6% 27.4% 25.1% 17.5% 14.7% 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 10.2% 9.6% 26.3% 29.3% 33.5% 46.0% 65.0% 57.5% 47.0% 47.0% 49.4% 39.2% 23.3% 31.1% 25.2% 22.4% 15.7% 13.4% 1.5% 1.8% 1.5% 1.3% 1.4% 1.4% Cash & Cash Equivalents Gross Fixed Income Securities Gross Loans Other Assets 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 Balance Sheet Allocation
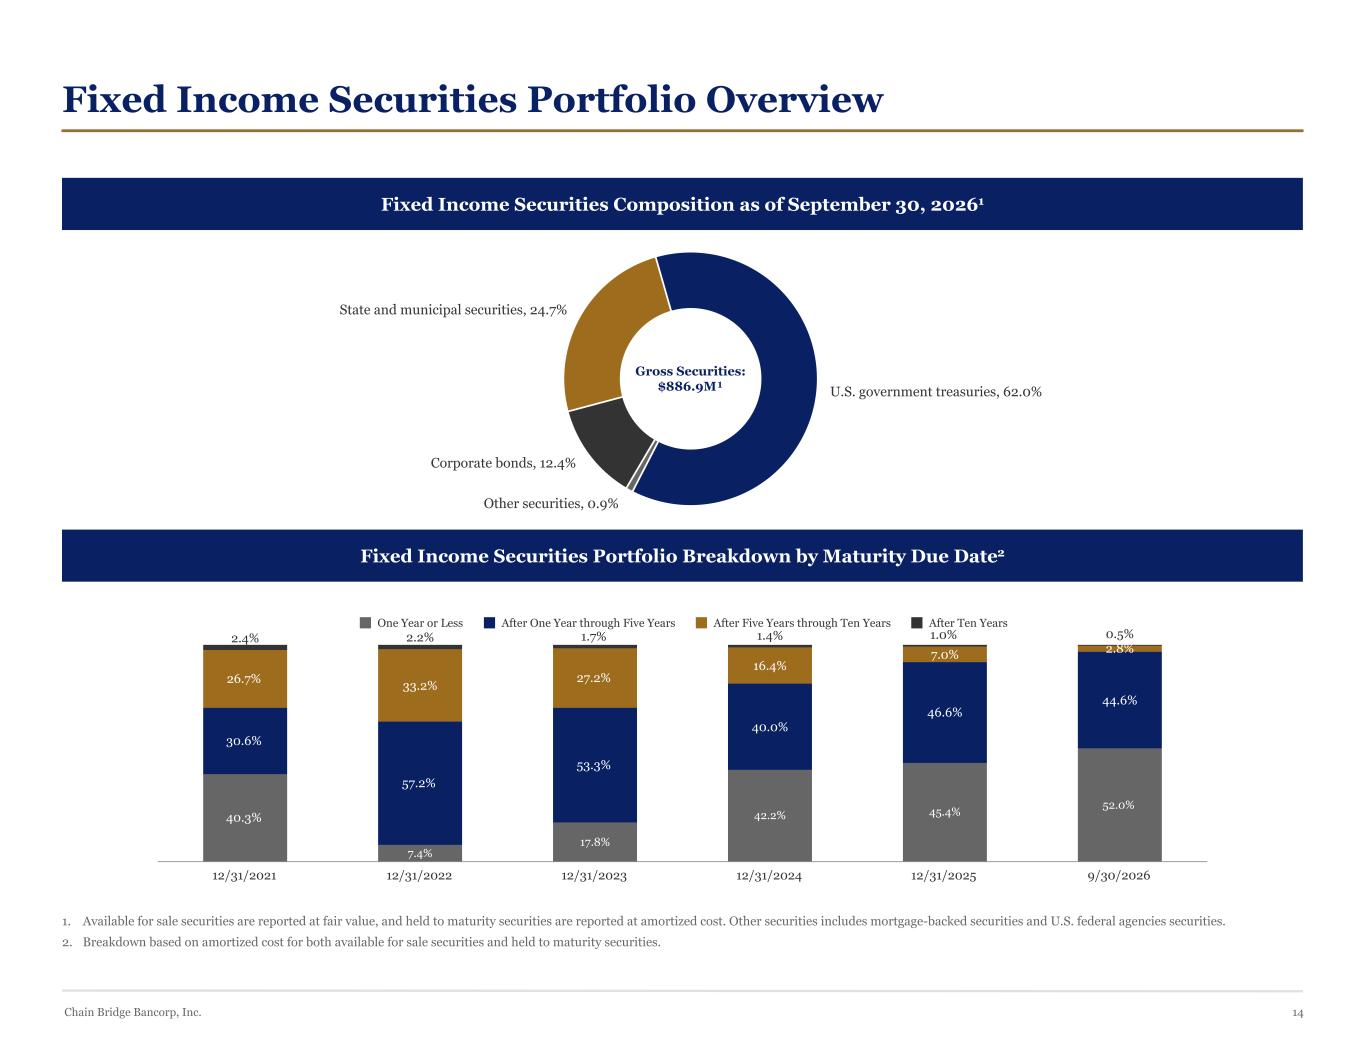
14Chain Bridge Bancorp, Inc. 1. Available for sale securities are reported at fair value, and held to maturity securities are reported at amortized cost. Other securities includes mortgage-backed securities and U.S. federal agencies securities. 2. Breakdown based on amortized cost for both available for sale securities and held to maturity securities. Gross Securities: $886.9M¹ Fixed Income Securities Portfolio Breakdown by Maturity Due Date2 Fixed Income Securities Composition as of September 30, 20261 40.3% 7.4% 17.8% 42.2% 45.4% 52.0% 30.6% 57.2% 53.3% 40.0% 46.6% 44.6% 26.7% 33.2% 27.2% 16.4% 7.0% 2.8% 2.4% 2.2% 1.7% 1.4% 1.0% 0.5% One Year or Less After One Year through Five Years After Five Years through Ten Years After Ten Years 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 U.S. government treasuries, 62.0% Other securities, 0.9% Corporate bonds, 12.4% State and municipal securities, 24.7% Fixed Income Securities Portfolio Overview
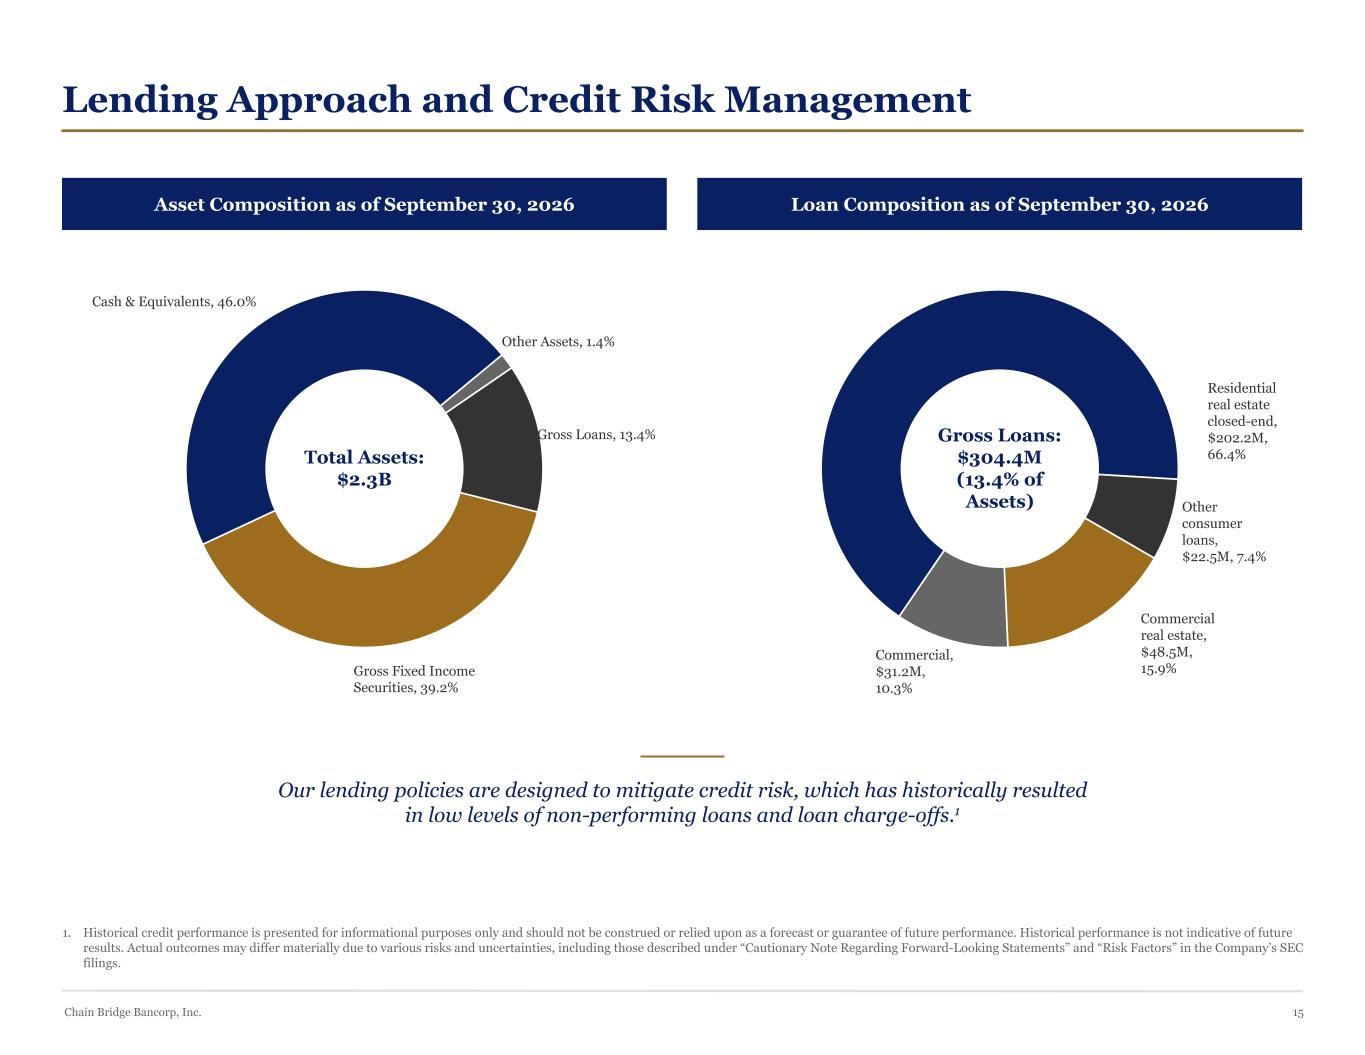
15Chain Bridge Bancorp, Inc. Loan Composition as of September 30, 2026Asset Composition as of September 30, 2026 Total Assets: $2.3B Gross Loans: $304.4M (13.4% of Assets) Gross Fixed Income Securities, 39.2% Cash & Equivalents, 46.0% Other Assets, 1.4% Gross Loans, 13.4% Commercial real estate, $48.5M, 15.9% Commercial, $31.2M, 10.3% Residential real estate closed-end, $202.2M, 66.4% Other consumer loans, $22.5M, 7.4% 1. Historical credit performance is presented for informational purposes only and should not be construed or relied upon as a forecast or guarantee of future performance. Historical performance is not indicative of future results. Actual outcomes may differ materially due to various risks and uncertainties, including those described under “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in the Company’s SEC filings. Lending Approach and Credit Risk Management Our lending policies are designed to mitigate credit risk, which has historically resulted in low levels of non-performing loans and loan charge-offs.1
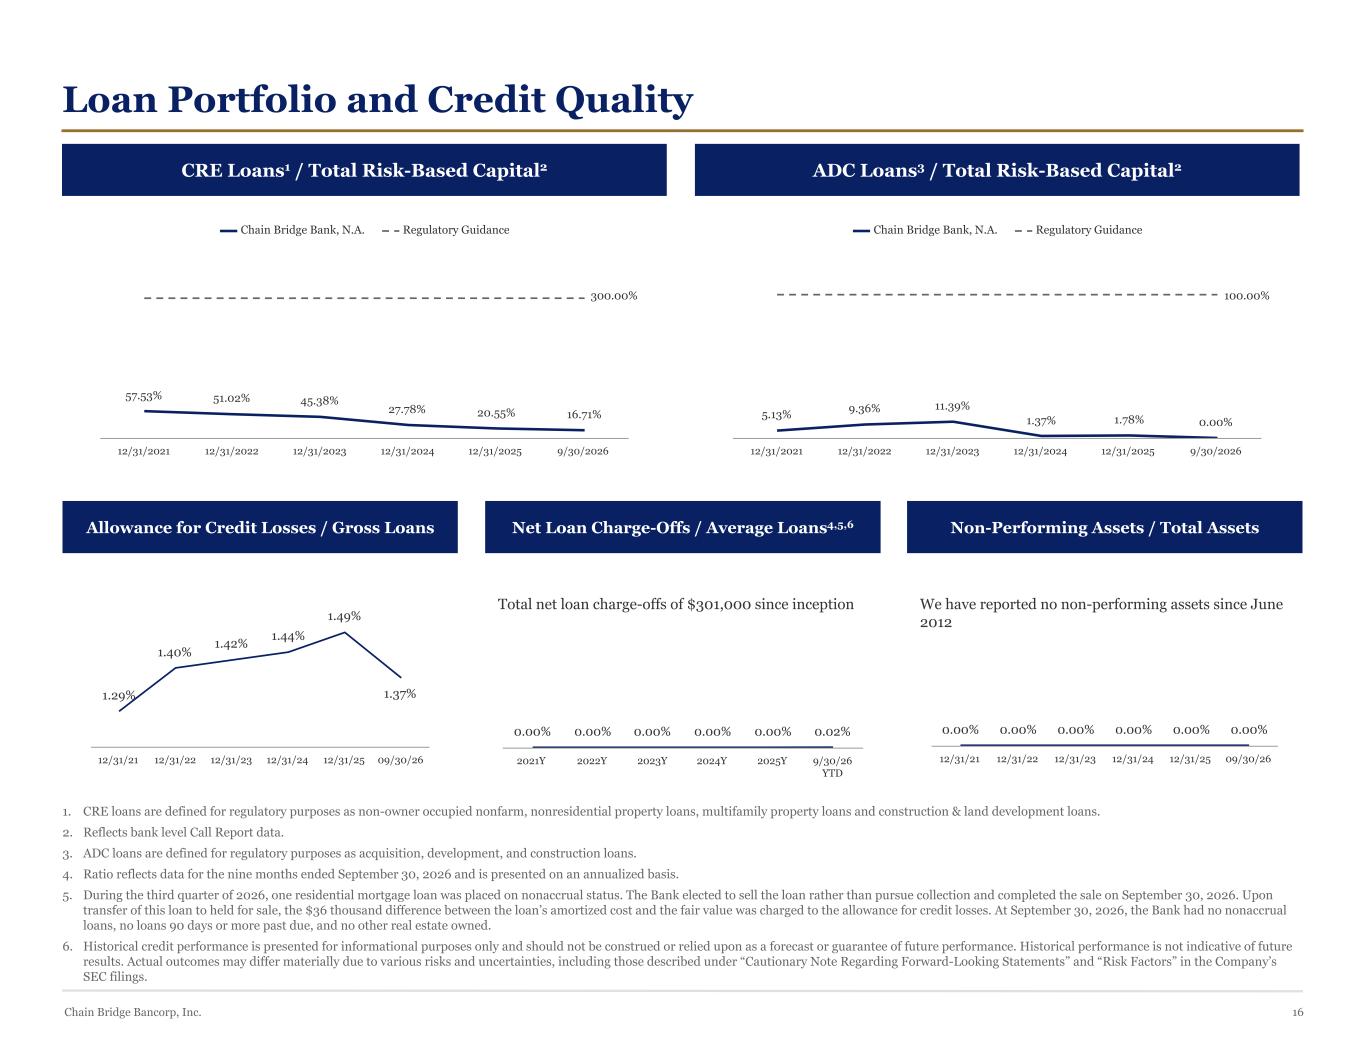
16Chain Bridge Bancorp, Inc. 1. CRE loans are defined for regulatory purposes as non-owner occupied nonfarm, nonresidential property loans, multifamily property loans and construction & land development loans. 2. Reflects bank level Call Report data. 3. ADC loans are defined for regulatory purposes as acquisition, development, and construction loans. 4. Ratio reflects data for the nine months ended September 30, 2026 and is presented on an annualized basis. 5. During the third quarter of 2026, one residential mortgage loan was placed on nonaccrual status. The Bank elected to sell the loan rather than pursue collection and completed the sale on September 30, 2026. Upon transfer of this loan to held for sale, the $36 thousand difference between the loan’s amortized cost and the fair value was charged to the allowance for credit losses. At September 30, 2026, the Bank had no nonaccrual loans, no loans 90 days or more past due, and no other real estate owned. 6. Historical credit performance is presented for informational purposes only and should not be construed or relied upon as a forecast or guarantee of future performance. Historical performance is not indicative of future results. Actual outcomes may differ materially due to various risks and uncertainties, including those described under “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in the Company’s SEC filings. Net Loan Charge-Offs / Average Loans4,5,6Allowance for Credit Losses / Gross Loans ADC Loans3 / Total Risk-Based Capital2CRE Loans1 / Total Risk-Based Capital2 Non-Performing Assets / Total Assets 0.00% 0.00% 0.00% 0.00% 0.00% 0.00% 12/31/21 12/31/22 12/31/23 12/31/24 12/31/25 09/30/26 0.00% 0.00% 0.00% 0.00% 0.00% 0.02% 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/26 YTD 1.29% 1.40% 1.42% 1.44% 1.49% 1.37% 12/31/21 12/31/22 12/31/23 12/31/24 12/31/25 09/30/26 57.53% 51.02% 45.38% 27.78% 20.55% 16.71% Chain Bridge Bank, N.A. Regulatory Guidance 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 300.00% 5.13% 9.36% 11.39% 1.37% 1.78% 0.00% Chain Bridge Bank, N.A. Regulatory Guidance 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 100.00% Loan Portfolio and Credit Quality Total net loan charge-offs of $301,000 since inception We have reported no non-performing assets since June 2012
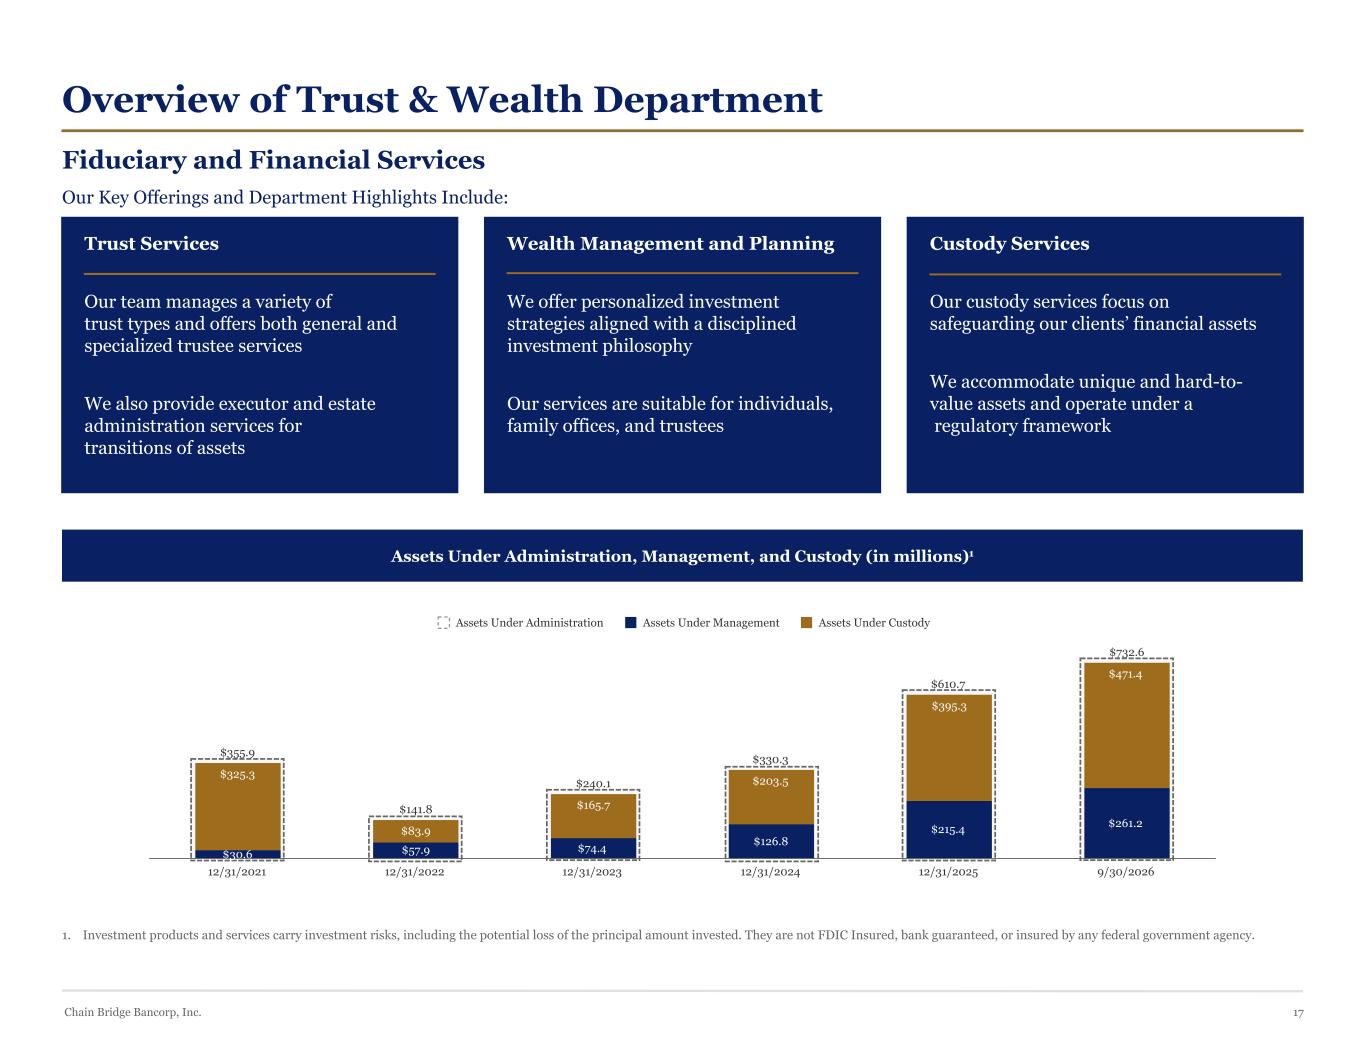
17Chain Bridge Bancorp, Inc. Our Key Offerings and Department Highlights Include: Fiduciary and Financial Services Trust Services Our team manages a variety of trust types and offers both general and specialized trustee services We also provide executor and estate administration services for transitions of assets Wealth Management and Planning We offer personalized investment strategies aligned with a disciplined investment philosophy Our services are suitable for individuals, family offices, and trustees Custody Services Our custody services focus on safeguarding our clients’ financial assets We accommodate unique and hard-to- value assets and operate under a regulatory framework Assets Under Administration, Management, and Custody (in millions)1 1. Investment products and services carry investment risks, including the potential loss of the principal amount invested. They are not FDIC Insured, bank guaranteed, or insured by any federal government agency. Overview of Trust & Wealth Department $355.9 $141.8 $240.1 $330.3 $610.7 $732.6 $30.6 $57.9 $74.4 $126.8 $215.4 $261.2 $325.3 $83.9 $165.7 $203.5 $395.3 $471.4 Assets Under Administration Assets Under Management Assets Under Custody 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026
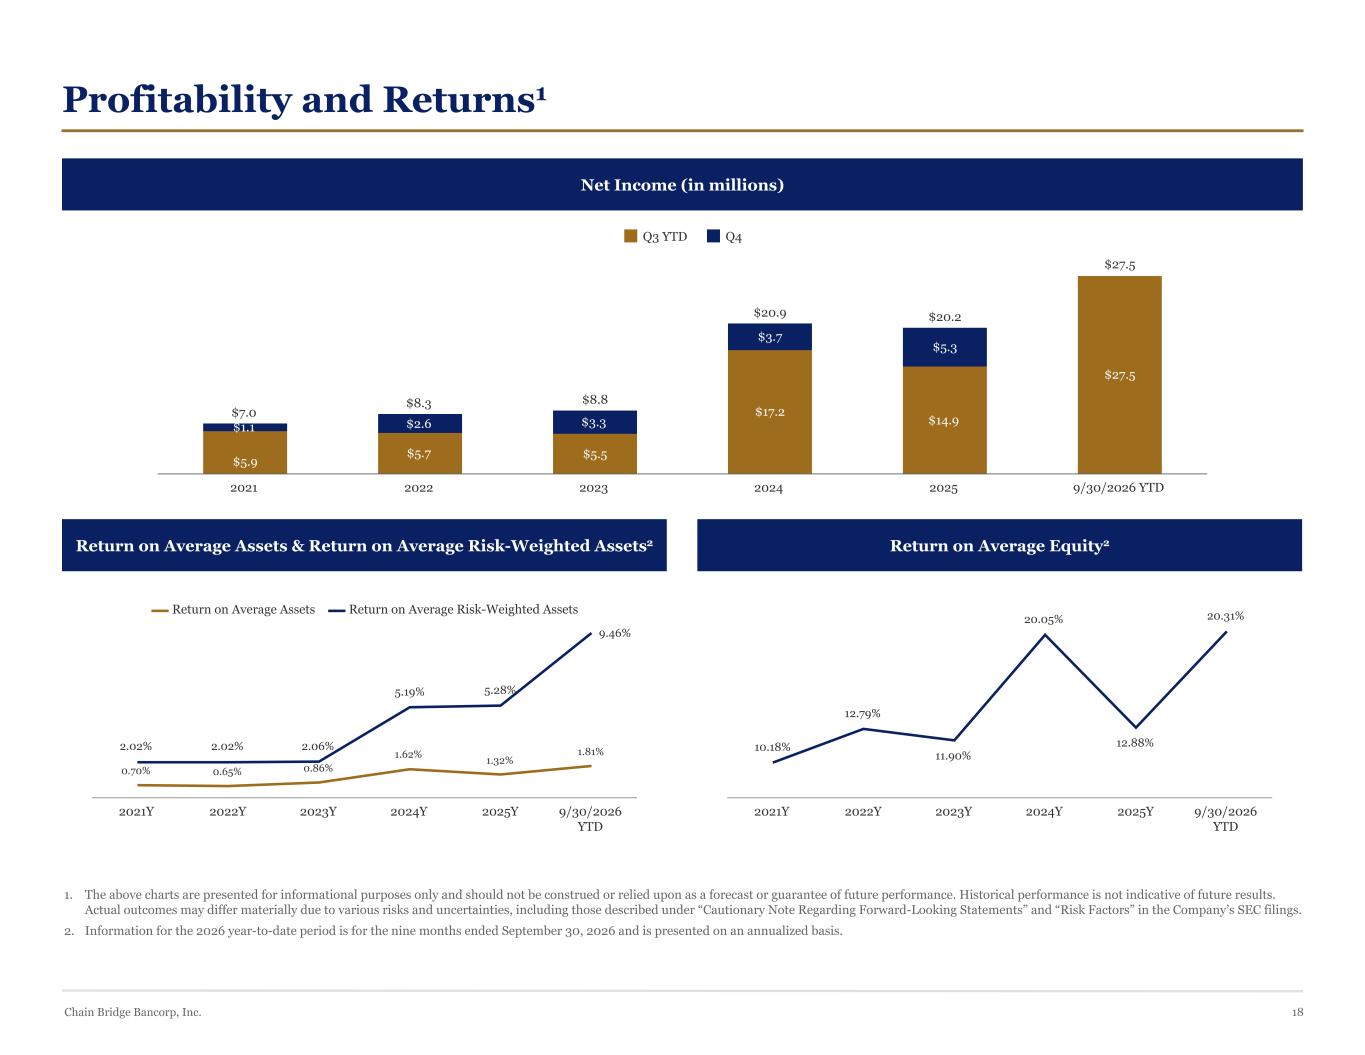
18Chain Bridge Bancorp, Inc. 1. The above charts are presented for informational purposes only and should not be construed or relied upon as a forecast or guarantee of future performance. Historical performance is not indicative of future results. Actual outcomes may differ materially due to various risks and uncertainties, including those described under “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in the Company’s SEC filings. 2. Information for the 2026 year-to-date period is for the nine months ended September 30, 2026 and is presented on an annualized basis. Return on Average Equity2Return on Average Assets & Return on Average Risk-Weighted Assets2 Net Income (in millions) 2.02% 2.02% 2.06% 5.19% 5.28% 9.46% 0.70% 0.65% 0.86% 1.62% 1.32% 1.81% Return on Average Assets Return on Average Risk-Weighted Assets 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD 10.18% 12.79% 11.90% 20.05% 12.88% 20.31% 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD $7.0 $8.3 $8.8 $20.9 $20.2 $27.5 $5.9 $5.7 $5.5 $17.2 $14.9 $27.5 $1.1 $2.6 $3.3 $3.7 $5.3 Q3 YTD Q4 2021 2022 2023 2024 2025 9/30/2026 YTD Profitability and Returns1
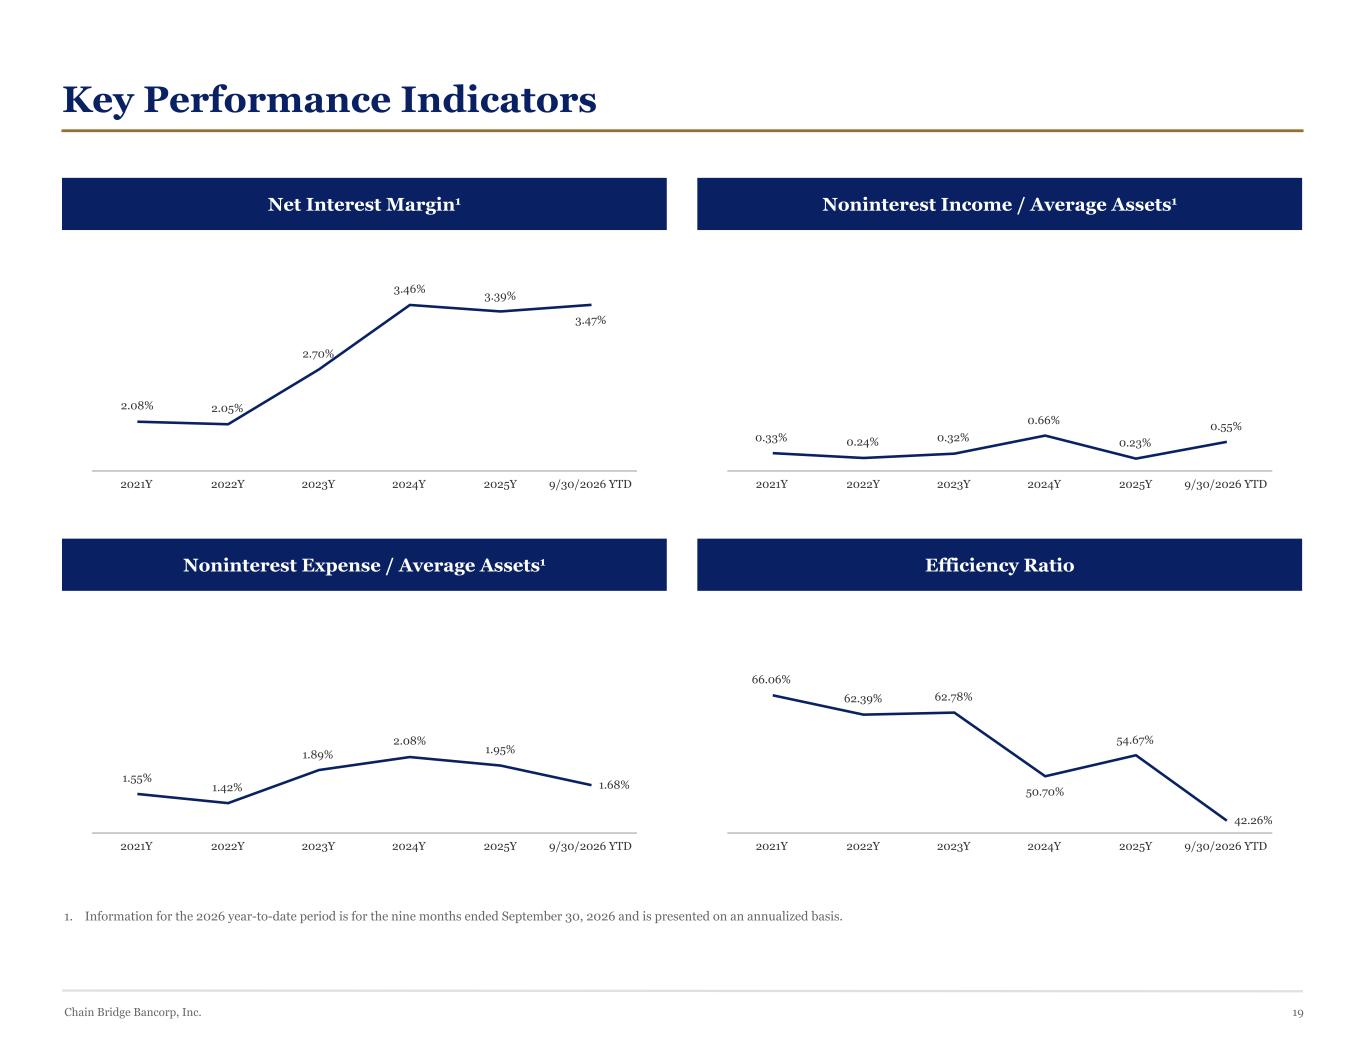
19Chain Bridge Bancorp, Inc. 1. Information for the 2026 year-to-date period is for the nine months ended September 30, 2026 and is presented on an annualized basis. Efficiency RatioNoninterest Expense / Average Assets1 Noninterest Income / Average Assets1Net Interest Margin1 2.08% 2.05% 2.70% 3.46% 3.39% 3.47% 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD 66.06% 62.39% 62.78% 50.70% 54.67% 42.26% 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD 0.33% 0.24% 0.32% 0.66% 0.23% 0.55% 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD 1.55% 1.42% 1.89% 2.08% 1.95% 1.68% 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD Key Performance Indicators
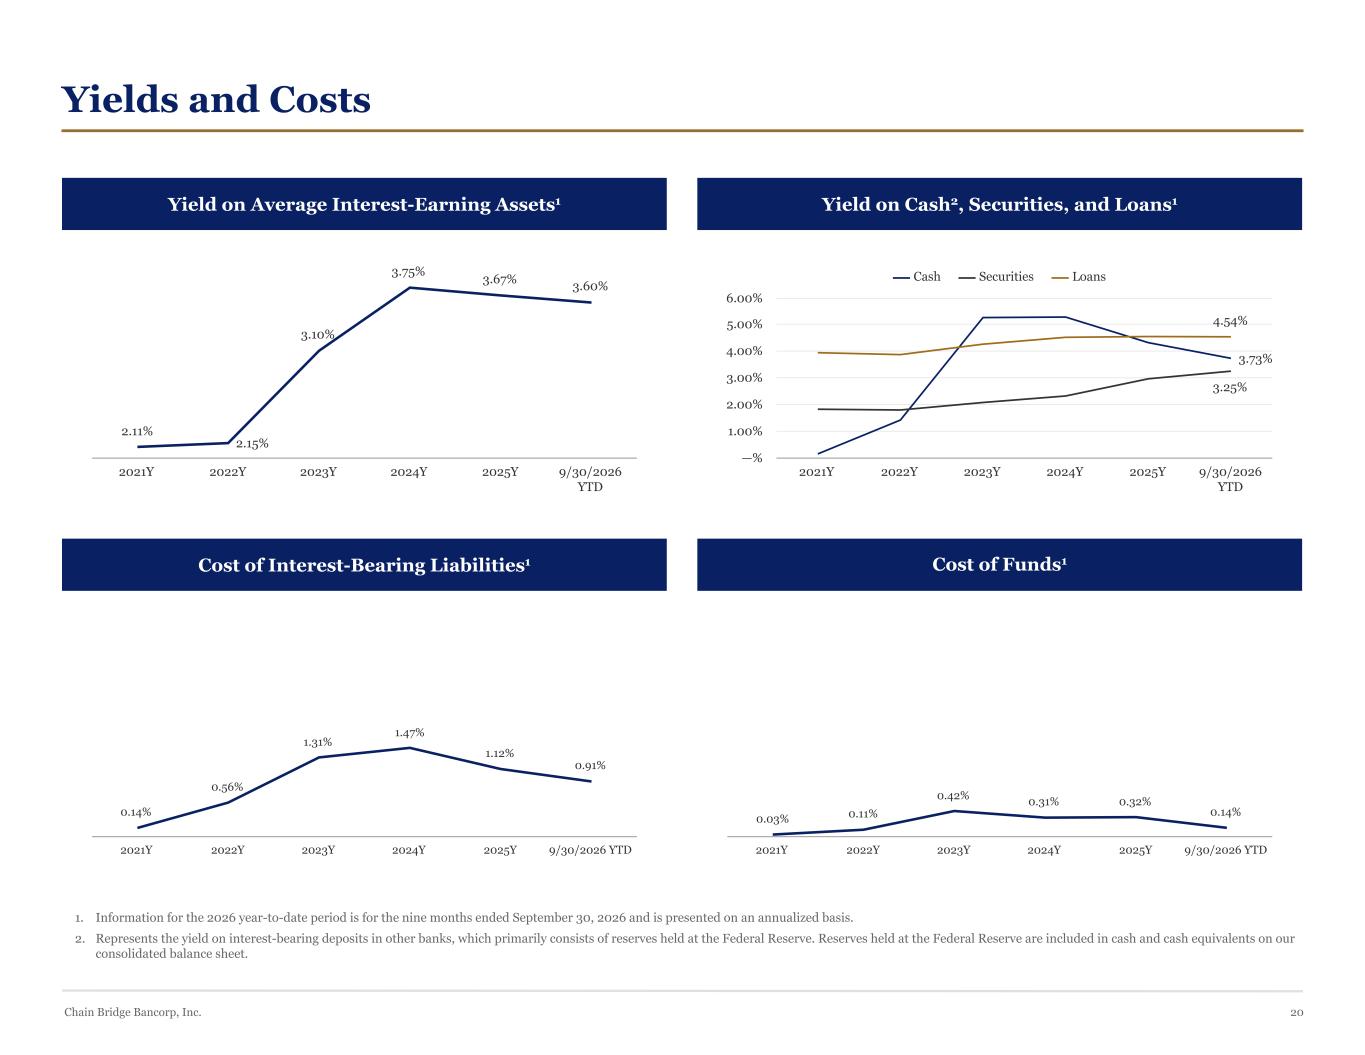
20Chain Bridge Bancorp, Inc. 1. Information for the 2026 year-to-date period is for the nine months ended September 30, 2026 and is presented on an annualized basis. 2. Represents the yield on interest-bearing deposits in other banks, which primarily consists of reserves held at the Federal Reserve. Reserves held at the Federal Reserve are included in cash and cash equivalents on our consolidated balance sheet. Yield on Cash2, Securities, and Loans1 Yields and Costs Cost of Funds1Cost of Interest-Bearing Liabilities1 0.03% 0.11% 0.42% 0.31% 0.32% 0.14% 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD Yield on Average Interest-Earning Assets1 3.73% 3.25% 4.54% Cash Securities Loans 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD —% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% 2.11% 2.15% 3.10% 3.75% 3.67% 3.60% 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD 0.14% 0.56% 1.31% 1.47% 1.12% 0.91% 2021Y 2022Y 2023Y 2024Y 2025Y 9/30/2026 YTD
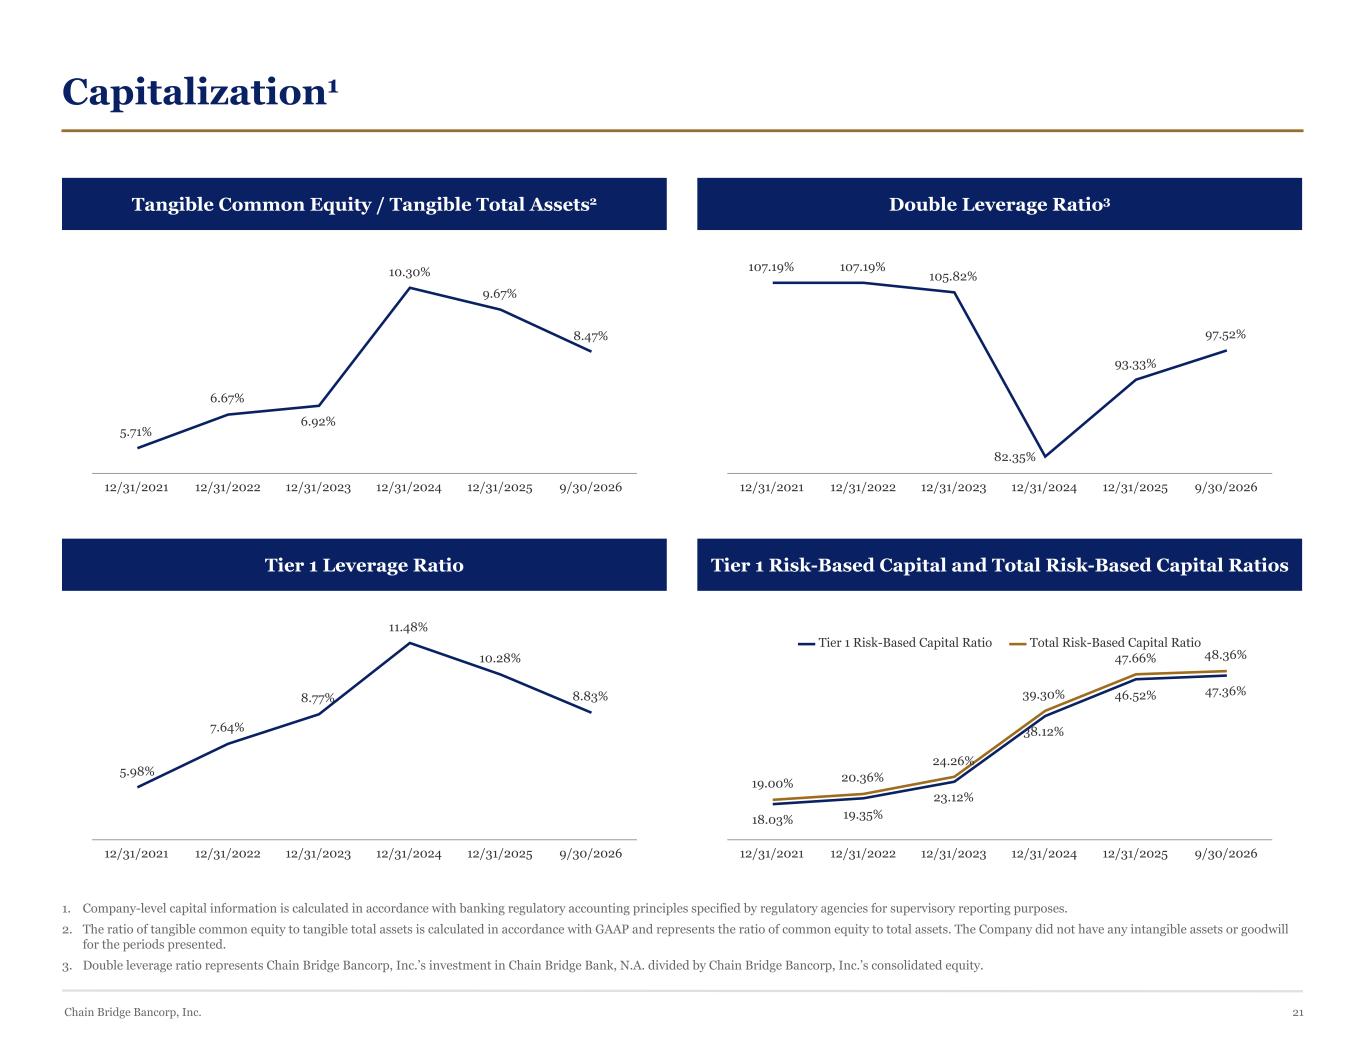
21Chain Bridge Bancorp, Inc. 1. Company-level capital information is calculated in accordance with banking regulatory accounting principles specified by regulatory agencies for supervisory reporting purposes. 2. The ratio of tangible common equity to tangible total assets is calculated in accordance with GAAP and represents the ratio of common equity to total assets. The Company did not have any intangible assets or goodwill for the periods presented. 3. Double leverage ratio represents Chain Bridge Bancorp, Inc.’s investment in Chain Bridge Bank, N.A. divided by Chain Bridge Bancorp, Inc.’s consolidated equity. Tier 1 Risk-Based Capital and Total Risk-Based Capital RatiosTier 1 Leverage Ratio Tangible Common Equity / Tangible Total Assets2 Capitalization1 Double Leverage Ratio3 107.19% 107.19% 105.82% 82.35% 93.33% 97.52% 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 5.71% 6.67% 6.92% 10.30% 9.67% 8.47% 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 5.98% 7.64% 8.77% 11.48% 10.28% 8.83% 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 18.03% 19.35% 23.12% 38.12% 46.52% 47.36% 19.00% 20.36% 24.26% 39.30% 47.66% 48.36% Tier 1 Risk-Based Capital Ratio Total Risk-Based Capital Ratio 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026
22Chain Bridge Bancorp, Inc. Additional Information Where to Find More Information: ■ SEC Filings: www.sec.gov ■ Investor Relations Website: https://ir.chainbridgebank.com ■ Information Sourced from the Following Filings: – Consolidated Reports of Condition and Income for a Bank with Domestic Offices Only—FFIEC 041 (Report date: September 30, 2026) – Earnings Release (Dated October 28, 2026, as of September 30, 2026) – Annual Report to Security Holders on Form ARS (Dated April 28, 2026, as of December 31, 2025) – Annual Report on Form 10-K (Dated March 20, 2026, as of December 31, 2025) – Proxy Statement on Schedule 14A (Dated April 28, 2026, for Annual Meeting on June 17, 2026) – Registration Statement on Form S-1, as Amended (Dated September 30, 2024) Investor Relations Contact: Hilary E. Albrecht Senior Vice President, Corporate Secretary and Counsel Chain Bridge Bancorp, Inc. IR@chainbridgebank.com 703-748-2005
Appendix
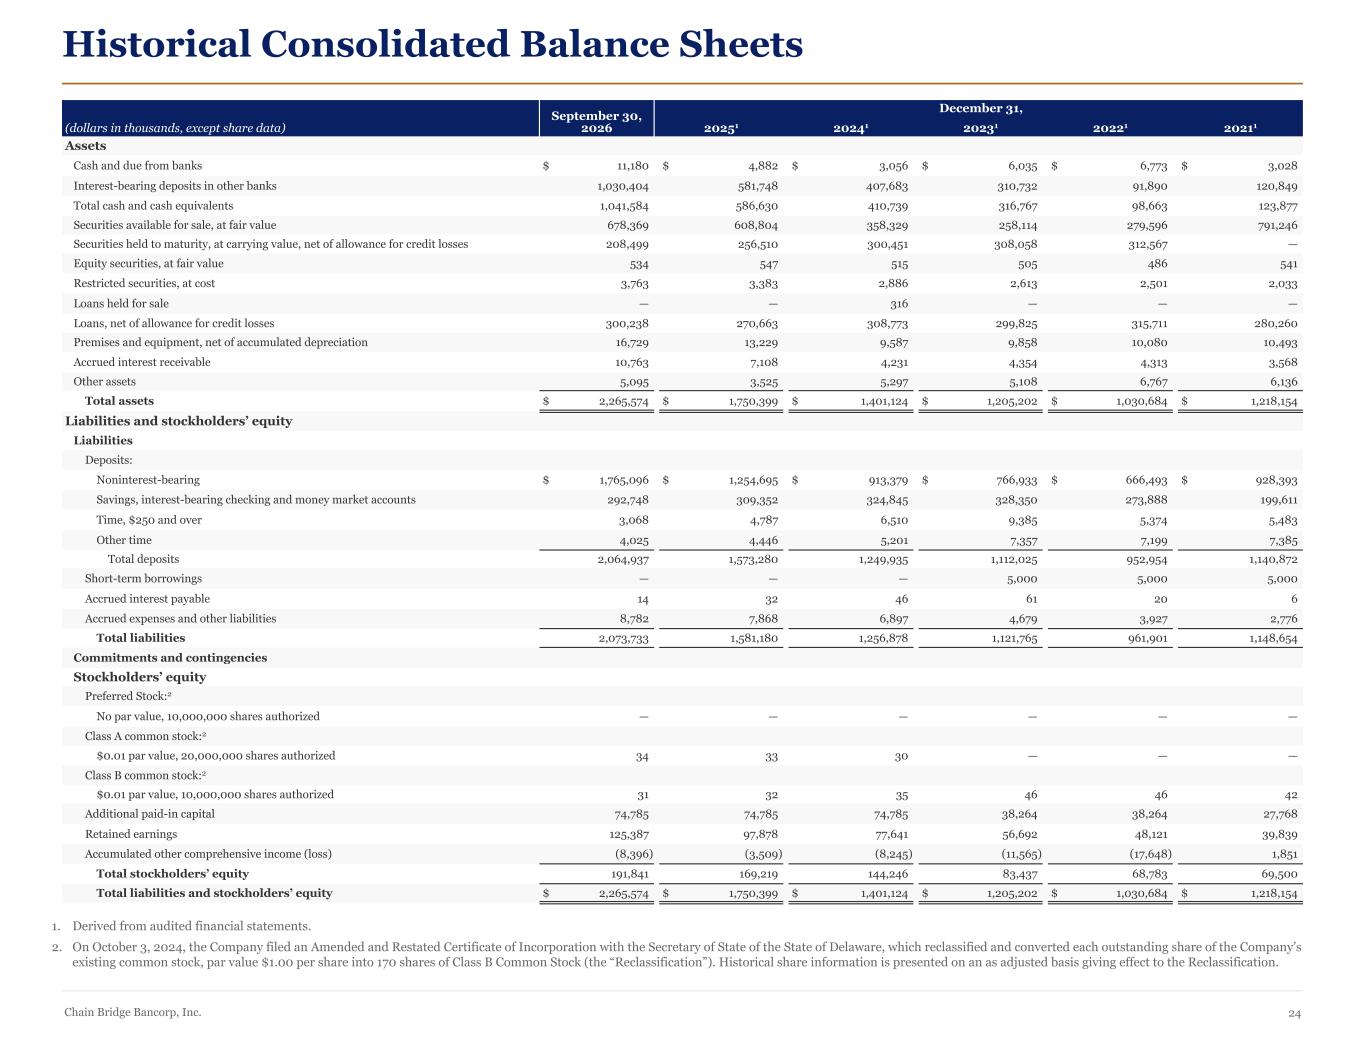
Chain Bridge Bancorp, Inc. 24 Historical Consolidated Balance Sheets September 30, 2026 December 31, (dollars in thousands, except share data) 20251 20241 20231 20221 20211 Assets Cash and due from banks $ 11,180 $ 4,882 $ 3,056 $ 6,035 $ 6,773 $ 3,028 Interest-bearing deposits in other banks 1,030,404 581,748 407,683 310,732 91,890 120,849 Total cash and cash equivalents 1,041,584 586,630 410,739 316,767 98,663 123,877 Securities available for sale, at fair value 678,369 608,804 358,329 258,114 279,596 791,246 Securities held to maturity, at carrying value, net of allowance for credit losses 208,499 256,510 300,451 308,058 312,567 — Equity securities, at fair value 534 547 515 505 486 541 Restricted securities, at cost 3,763 3,383 2,886 2,613 2,501 2,033 Loans held for sale — — 316 — — — Loans, net of allowance for credit losses 300,238 270,663 308,773 299,825 315,711 280,260 Premises and equipment, net of accumulated depreciation 16,729 13,229 9,587 9,858 10,080 10,493 Accrued interest receivable 10,763 7,108 4,231 4,354 4,313 3,568 Other assets 5,095 3,525 5,297 5,108 6,767 6,136 Total assets $ 2,265,574 $ 1,750,399 $ 1,401,124 $ 1,205,202 $ 1,030,684 $ 1,218,154 Liabilities and stockholders’ equity Liabilities Deposits: Noninterest-bearing $ 1,765,096 $ 1,254,695 $ 913,379 $ 766,933 $ 666,493 $ 928,393 Savings, interest-bearing checking and money market accounts 292,748 309,352 324,845 328,350 273,888 199,611 Time, $250 and over 3,068 4,787 6,510 9,385 5,374 5,483 Other time 4,025 4,446 5,201 7,357 7,199 7,385 Total deposits 2,064,937 1,573,280 1,249,935 1,112,025 952,954 1,140,872 Short-term borrowings — — — 5,000 5,000 5,000 Accrued interest payable 14 32 46 61 20 6 Accrued expenses and other liabilities 8,782 7,868 6,897 4,679 3,927 2,776 Total liabilities 2,073,733 1,581,180 1,256,878 1,121,765 961,901 1,148,654 Commitments and contingencies Stockholders’ equity Preferred Stock:2 No par value, 10,000,000 shares authorized — — — — — — Class A common stock:2 $0.01 par value, 20,000,000 shares authorized 34 33 30 — — — Class B common stock:2 $0.01 par value, 10,000,000 shares authorized 31 32 35 46 46 42 Additional paid-in capital 74,785 74,785 74,785 38,264 38,264 27,768 Retained earnings 125,387 97,878 77,641 56,692 48,121 39,839 Accumulated other comprehensive income (loss) (8,396) (3,509) (8,245) (11,565) (17,648) 1,851 Total stockholders’ equity 191,841 169,219 144,246 83,437 68,783 69,500 Total liabilities and stockholders’ equity $ 2,265,574 $ 1,750,399 $ 1,401,124 $ 1,205,202 $ 1,030,684 $ 1,218,154 1. Derived from audited financial statements. 2. On October 3, 2024, the Company filed an Amended and Restated Certificate of Incorporation with the Secretary of State of the State of Delaware, which reclassified and converted each outstanding share of the Company’s existing common stock, par value $1.00 per share into 170 shares of Class B Common Stock (the “Reclassification”). Historical share information is presented on an as adjusted basis giving effect to the Reclassification.
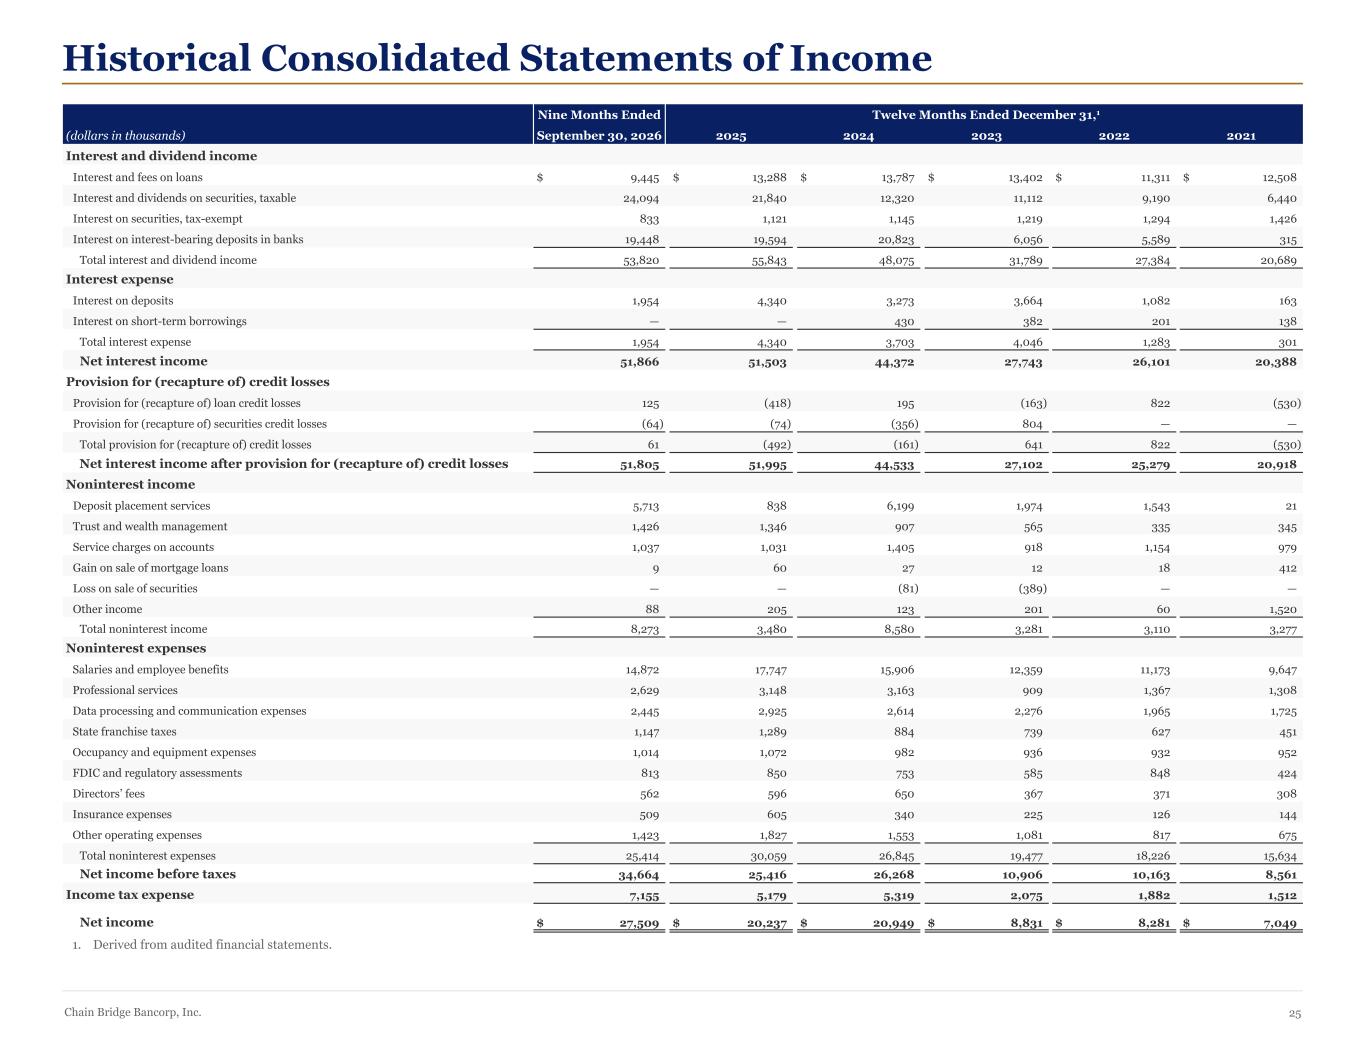
Chain Bridge Bancorp, Inc. 25 Historical Consolidated Statements of Income Nine Months Ended Twelve Months Ended December 31,1 (dollars in thousands) September 30, 2026 2025 2024 2023 2022 2021 Interest and dividend income Interest and fees on loans $ 9,445 $ 13,288 $ 13,787 $ 13,402 $ 11,311 $ 12,508 Interest and dividends on securities, taxable 24,094 21,840 12,320 11,112 9,190 6,440 Interest on securities, tax-exempt 833 1,121 1,145 1,219 1,294 1,426 Interest on interest-bearing deposits in banks 19,448 19,594 20,823 6,056 5,589 315 Total interest and dividend income 53,820 55,843 48,075 31,789 27,384 20,689 Interest expense Interest on deposits 1,954 4,340 3,273 3,664 1,082 163 Interest on short-term borrowings — — 430 382 201 138 Total interest expense 1,954 4,340 3,703 4,046 1,283 301 Net interest income 51,866 51,503 44,372 27,743 26,101 20,388 Provision for (recapture of) credit losses Provision for (recapture of) loan credit losses 125 (418) 195 (163) 822 (530) Provision for (recapture of) securities credit losses (64) (74) (356) 804 — — Total provision for (recapture of) credit losses 61 (492) (161) 641 822 (530) Net interest income after provision for (recapture of) credit losses 51,805 51,995 44,533 27,102 25,279 20,918 Noninterest income Deposit placement services 5,713 838 6,199 1,974 1,543 21 Trust and wealth management 1,426 1,346 907 565 335 345 Service charges on accounts 1,037 1,031 1,405 918 1,154 979 Gain on sale of mortgage loans 9 60 27 12 18 412 Loss on sale of securities — — (81) (389) — — Other income 88 205 123 201 60 1,520 Total noninterest income 8,273 3,480 8,580 3,281 3,110 3,277 Noninterest expenses Salaries and employee benefits 14,872 17,747 15,906 12,359 11,173 9,647 Professional services 2,629 3,148 3,163 909 1,367 1,308 Data processing and communication expenses 2,445 2,925 2,614 2,276 1,965 1,725 State franchise taxes 1,147 1,289 884 739 627 451 Occupancy and equipment expenses 1,014 1,072 982 936 932 952 FDIC and regulatory assessments 813 850 753 585 848 424 Directors’ fees 562 596 650 367 371 308 Insurance expenses 509 605 340 225 126 144 Other operating expenses 1,423 1,827 1,553 1,081 817 675 Total noninterest expenses 25,414 30,059 26,845 19,477 18,226 15,634 Net income before taxes 34,664 25,416 26,268 10,906 10,163 8,561 Income tax expense 7,155 5,179 5,319 2,075 1,882 1,512 Net income $ 27,509 $ 20,237 $ 20,949 $ 8,831 $ 8,281 $ 7,049 1. Derived from audited financial statements.
Chain Bridge Bancorp, Inc. | NYSE: CBNA | ir.chainbridgebank.com